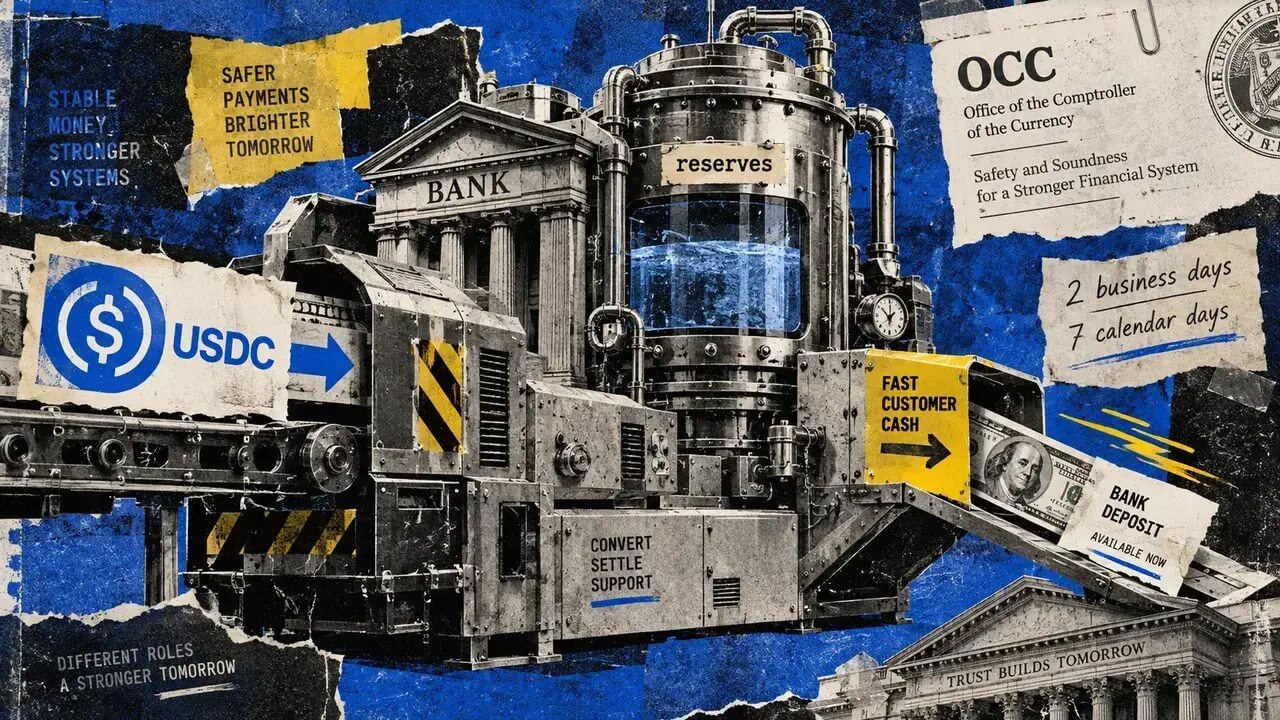
Eight banking organizations have requested that lawmakers establish stricter regulations on stablecoin rewards before the Senate votes on the CLARITY Act this week. The banking groups argue that when deposits move to dollar-pegged stablecoins offering incentives, banks lose a reliable and inexpensive funding source.
Banks use approximately 80% of deposits to finance loans, making stablecoin incentives relevant to both funding costs and control of dollar-based payment systems. In a letter to Senate Majority Leader John Thune and Senate Minority Leader Chuck Schumer, organizations including the American Bankers Association, Bank Policy Institute, and Independent Community Bankers of America requested specific language changes to the bill.
The banking groups asked the Senate to remove the word "solely" from the payment definition, replace "economically or functionally equivalent" with "substantially similar," and strike references to rewards based on balance, duration, or time in business. The request follows support from 80 state bankers' associations for stricter language on September 10.
The Stablecoin Market Context
Stablecoins are designed to mimic assets like the dollar, with nearly 98% of stablecoins valued in dollars, according to a Bank for International Settlements paper. The IMF estimated the stablecoin market at approximately $300 billion in August.
The 2025 GENIUS Act prevents stablecoin issuers from providing interest or yield directly. However, White House analysis indicated the legislation does not explicitly ban reward distribution by affiliates and third parties. The CLARITY Act would clarify how much such arrangements can continue.
Government Analysis Suggests Limited Impact
The White House Council of Economic Advisers conducted an April study estimating that banning stablecoin yields would increase bank lending by only $2.1 billion, equivalent to 0.02%, while creating a net welfare loss of $800 million. Community bank lending would increase by approximately $500 million under this scenario.
Even under the CEA's unrealistic assumptions—including stablecoin usage six times higher than current levels and major changes to Federal Reserve monetary policy—estimated bank lending increases reached only 4.4%.
Legislative Changes and Industry Divisions
The updated CLARITY Act issued Sunday includes 126 significant amendments sought by Democrats. The bill tightens rules governing how public figures can benefit from cryptocurrencies and grants state attorneys general expanded law enforcement powers. Senator Cynthia Lummis stated the bill is ready to proceed, while Senator Elizabeth Warren's staff described ethics-related changes as "empty."
The legislation maintains prohibitions on passive stablecoin yields and rewards functioning like bank interest, while explicitly permitting transaction-based rewards. A new Treasury circuit-breaker mechanism allows emergency tightening if stablecoins demonstrably reduce community bank deposits. Stablecoin marketing as deposits remains explicitly prohibited.
The banking industry's position is not monolithic. Goldman Sachs, BNY Mellon, and Morgan Stanley have supported the legislation, diverging from retail-oriented banking groups. Some community banks are exploring stablecoin payment technology through partnerships, including Moov's network of over 1,000 institutions using Coinbase's stablecoin capabilities.
The Senate requires 60 votes to pass cloture on Tuesday's vote.