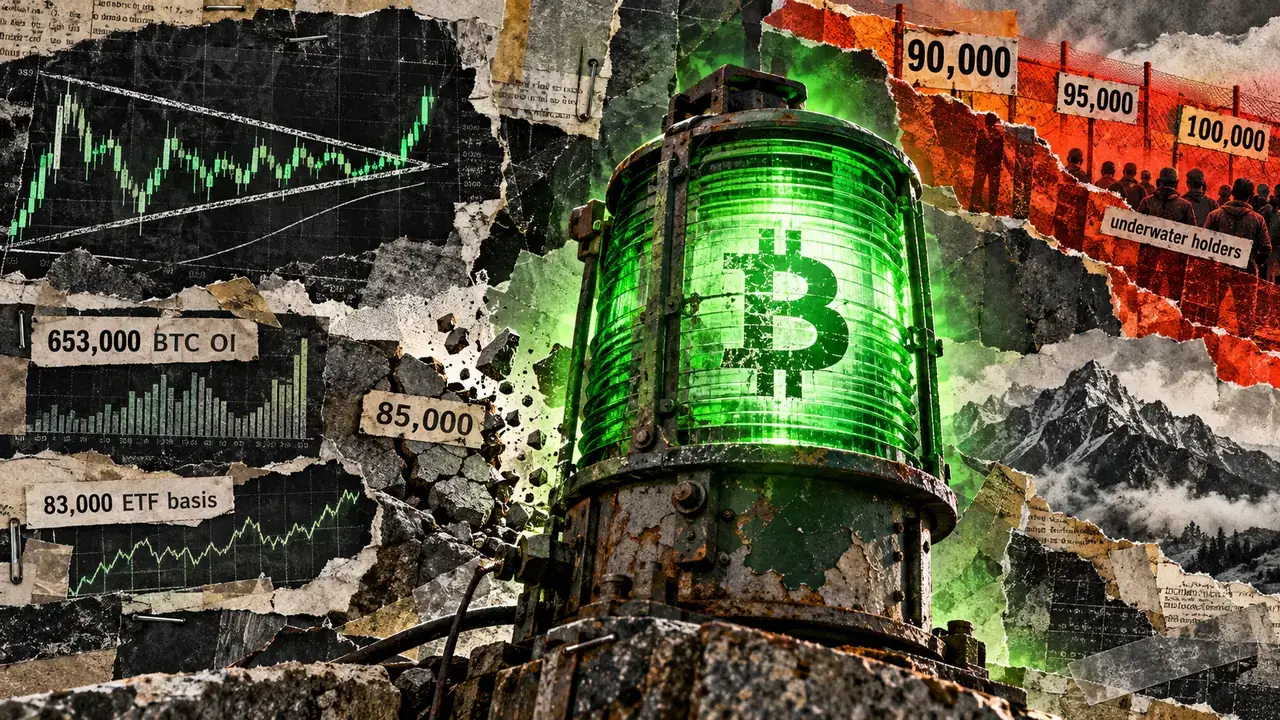
Bitcoin recently registered an intraday high of $87,000 after buyers broke through a sell wall around $85,000 that had previously stalled multiple advance attempts. According to Glassnode, some of those orders were filled while the remainder were withdrawn, leaving a smaller concentration of asks around $87,000 and reduced visible liquidity immediately above.
As the market approaches a test of $90,000, bands on CryptoQuant’s Bitcoin Accumulation Trend chart have started contracting. This setup mirrors a pattern observed prior to two sharp advances earlier in 2025, though analysts note that the limited historical occurrences make the pattern inconclusive.
Bitwise reports that Bitcoin has successfully reclaimed several major cost-basis thresholds, including the short-term holder cost basis near $73,000, a true market mean around $77,000, and the estimated average cost basis for spot exchange-traded fund investors near $83,000. Bitcoin also moved past the $85,000 short-term holder realized-price band.
With the $85,000 sell wall cleared, Bitcoin faces potential supply from investors nearing breakeven after months of losses. CryptoQuant analyst Darkfost estimates that holders who acquired assets 18 months to two years ago have an average cost basis near $88,350, while the six-to-12-month cohort sits around $89,200.
Bitwise valuation bands place the next short-term holder reference level around $90,000, followed by a two-standard-deviation level near $95,000, with Fibonacci frameworks pointing to levels near $92,000 and $100,000. Options traders are similarly positioned around this corridor, with Deribit data showing substantial call exposure at the $90,000, $95,000, and $100,000 strikes.
Meanwhile, speculative exposure has begun to recover. CoinGlass data indicates that Bitcoin open interest climbed to roughly $56.2 billion in the first two days of October, recovering from a drop to about $52 billion at the end of September. The macro environment also provided a boost following a weaker-than-expected US employment report for September, which drove down expectations for a Federal Reserve rate increase at the October meeting, lowered Treasury yields, and lifted equities.