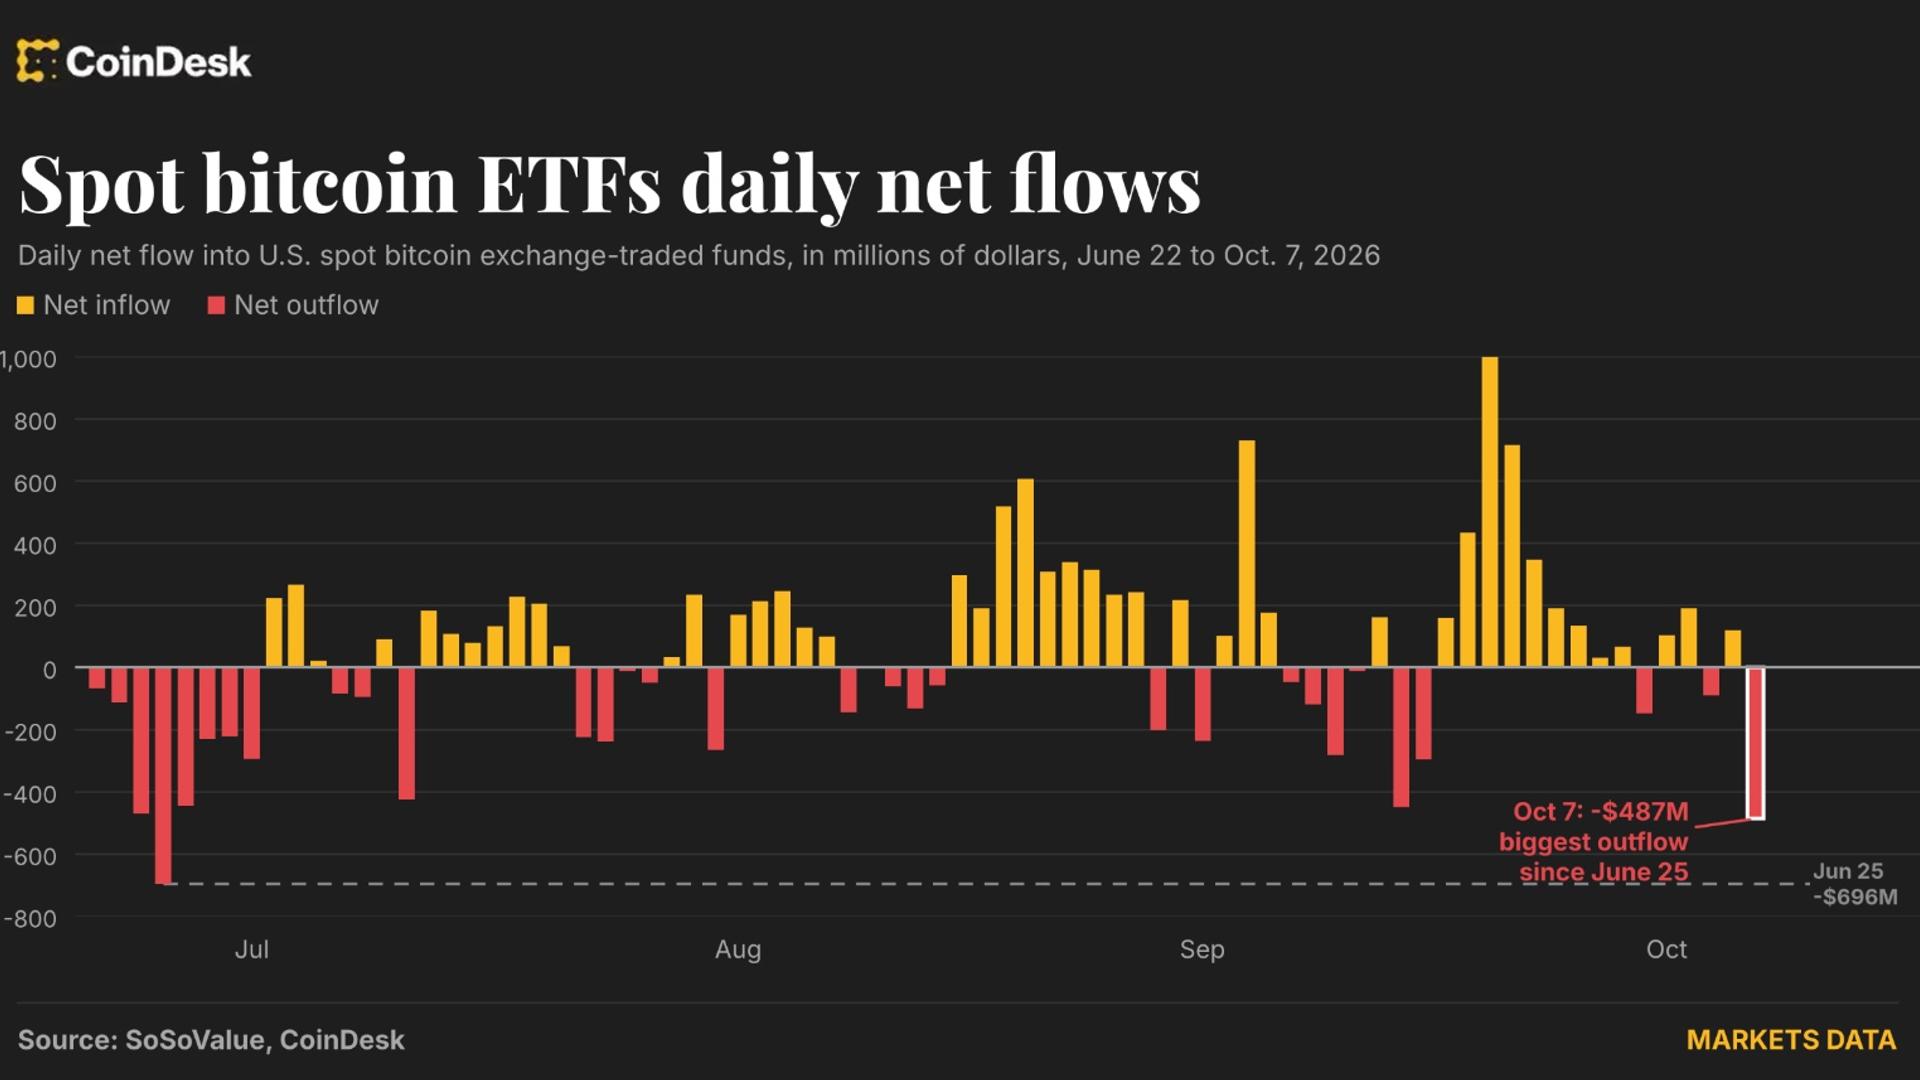
U.S. spot bitcoin ETFs registered net outflows of $487.1 million on Wednesday, the largest single-day outflow since June 25, according to flow data. The move signals a reversal in investor sentiment just a day after analysts indicated that sustained inflows would be needed to push bitcoin meaningfully above $87,000.
The outflow was statistically unusual, measuring 2.1 standard deviations below the 90-day average daily inflow of approximately $92 million. In normal distributions, roughly 95% of observations fall within two standard deviations of the mean, making Wednesday's event a rare occurrence.
Year-to-date flows remain modest. The spot ETFs have taken in a net $717 million through October 8, 2026, down from approximately $2.65 billion in net inflows during September. October has seen $165.6 million in net outflows so far, with the past six trading sessions alternating between small inflows and outflows.
Since beginning trading in January 2024, the funds have accumulated $57.33 billion in net inflows, though this cushion has been tested repeatedly. The funds bottomed at a net outflow of $5.76 billion in July.
Bitcoin traded near $83,000 following the outflow, hovering near a price floor that has held since September 21. Analysts noted that a sustained break below this level could expose support at $80,000 and threaten the bullish technical pattern on the daily chart.
According to FxPro chief market analyst Alex Kuptsikevich, the $80.5K–$81.5K range represents both last month's local highs and the 50-day moving average. He warned that weakness in this area could either attract bargain buyers for a rapid retest of highs, or force margin position liquidations leading to sharp declines toward $76,000 or $72,000.
Market headwinds include volatile Treasury note movements, geopolitical tensions between the U.S. and Iran that could spike oil prices, and weakening spot ETF inflows that were a major driver during the August-September rally.