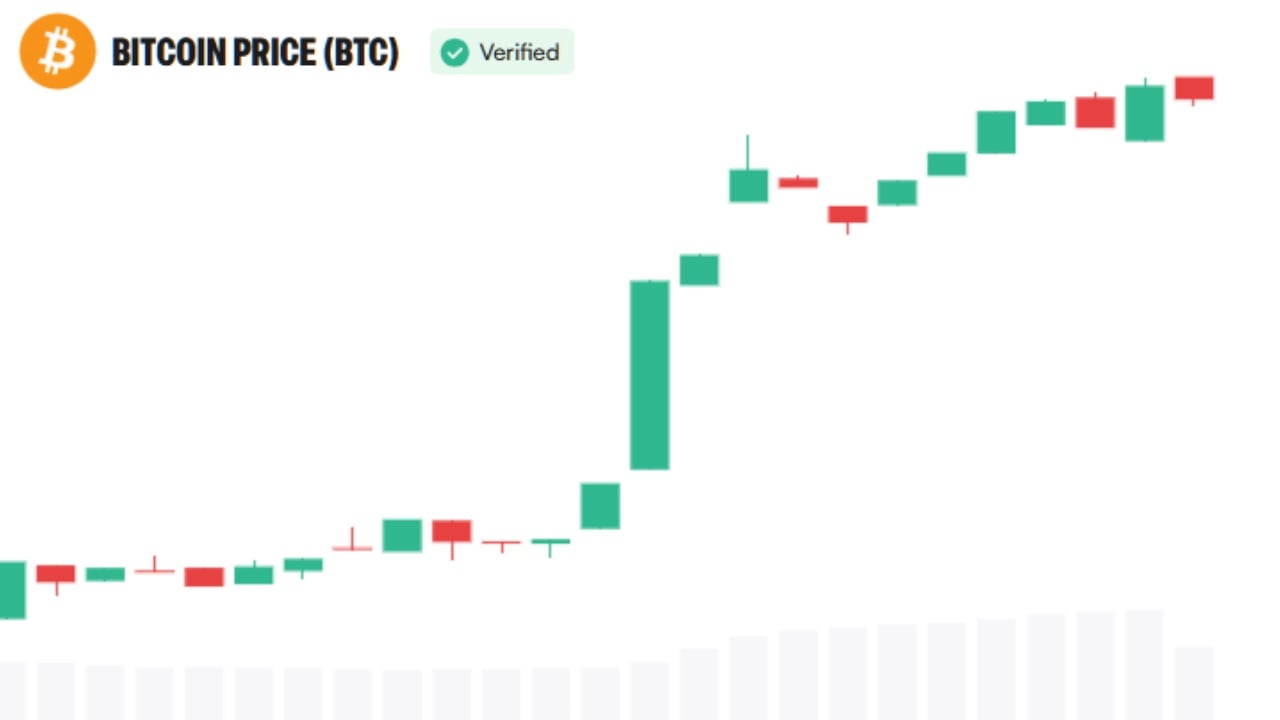
The amount of futures notional value backing Bitcoin on exchanges has declined to 0.24 times relative to spot, marking its lowest reading in two years. This metric reflects the total dollar value of outstanding futures contracts compared to underlying spot market activity.
Aggregate Bitcoin futures open interest has drawn down between 47% and 55% from peak levels, with total notional exposure fluctuating between $40 billion and $70 billion. Offshore Bitcoin futures activity has fallen roughly 97% from highs seen during the 2021 bull market.
CME Institutional Activity Weakens
CME Bitcoin futures, the primary venue for institutional participation, saw open interest and volume sink to 14-month lows earlier in the year. Daily open interest on the CME averaged under $8 billion in March, compared to tens of billions that previously rotated through the platform.
The basis trade, which involves buying spot Bitcoin and selling futures contracts at a premium, once generated annualized yields exceeding 20%. That compression to roughly 3 percent to 5 percent has reduced the incentive for such trades, given operational complexity and counterparty risk.
Leverage Migration to Perpetual Contracts
The decline in traditional futures notional does not indicate leverage has disappeared entirely from cryptocurrency markets. Perpetual contracts and options markets have absorbed much of the speculative activity that once concentrated in dated futures contracts.
On Binance, the dominant venue for crypto derivatives, the futures-to-spot deployment ratio has fluctuated between 8 and 9 times. Analysis indicated this reflects unstable market depth with diminished speculative engagement.
Positioning data shows leveraged funds have recently increased short positions while asset managers have built long exposure.
Implications for Price Discovery
Thin futures markets mean fewer arbitrage opportunities and reduced price discovery in the derivatives layer. This environment can leave spot prices more susceptible to idiosyncratic flows, such as large wallet movements or exchange-specific liquidity events, rather than being anchored by a robust derivatives complex.