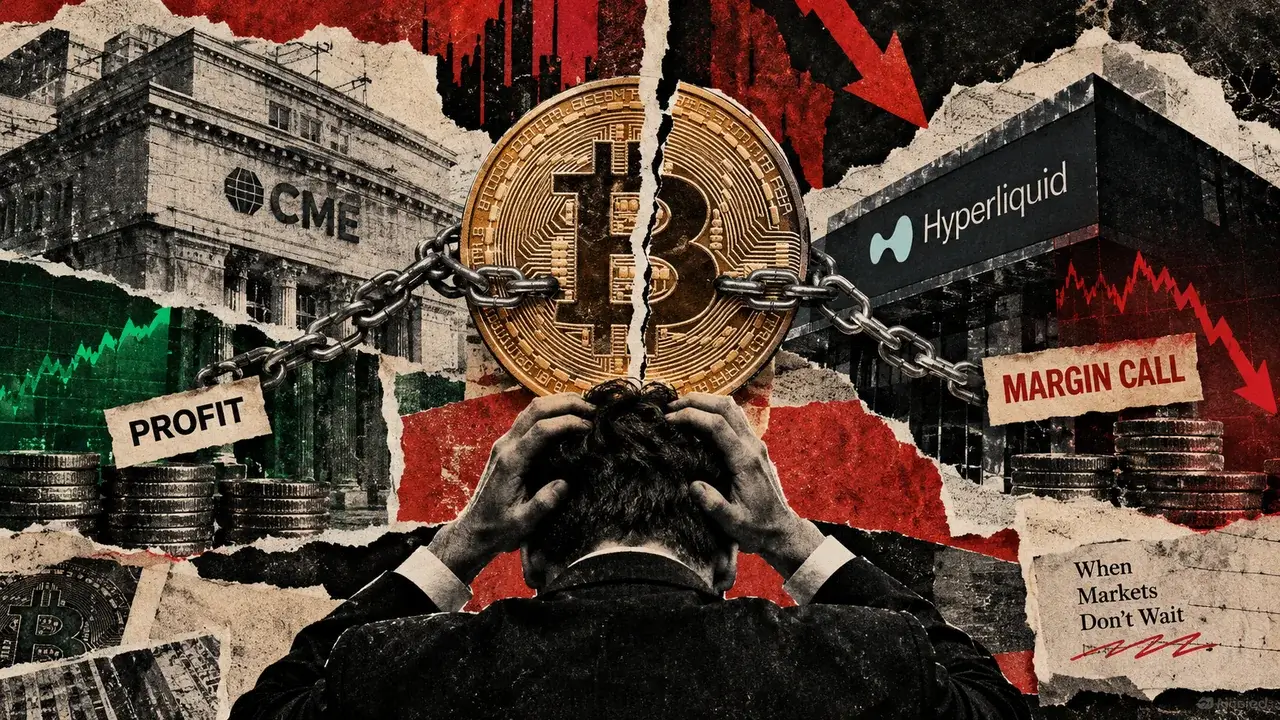
In institutional Bitcoin trading, a seemingly profitable hedge can collapse due to the mechanics of how exchanges manage collateral. A fund holding offsetting positions—long Bitcoin on one exchange and short on another—may face forced liquidation of one side while profits from the other sit inaccessible in a different account.
Consider a fund holding $4.5 million long on Hyperliquid and $4.5 million short on CME futures. If Bitcoin falls 20%, the short position gains roughly $900,000 while the long loses approximately the same amount. On paper, the hedge works as intended. However, each exchange manages its own margin requirements independently. Hyperliquid demands additional collateral to keep the losing position open, while CME's profits remain frozen in a separate account under different settlement rules. The fund must transfer profits or close both positions before Hyperliquid liquidates the long.
If withdrawals are delayed during a market downturn, the fund can find itself short of collateral in one account despite having sufficient assets across its portfolio. Once one side is liquidated, the remaining position becomes an unhedged directional bet.
Ian Weisberger, CEO of CoinRoutes, cited the October 2025 crypto crash as an example of how dangerous this separation can be. Traders with balanced portfolios suddenly faced exposure because individual exchanges closed positions without accounting for offsetting trades elsewhere.
Leverage Amplifies the Problem
The challenge intensifies when funds use borrowed capital and derivatives to amplify their positions. A fund depositing $1 million in USDC can theoretically control $9 million in Bitcoin exposure by borrowing an additional $2 million and using derivatives on each exchange to establish $4.5 million positions in both directions.
The fund wants to profit from small price discrepancies between markets, funding payments, or futures pricing differences—not directional price movement. But even a 1% gap between two $4.5 million positions amounts to a $45,000 difference. The fund must maintain enough collateral to survive such discrepancies, even as positions are meant to offset each other.
The more efficiently a fund deploys capital, the less money it keeps in reserve for emergencies. This creates a dependency on seamless access to funds across multiple platforms precisely when market disruptions make transfers slower or more expensive.
The Fragmentation of Crypto Markets
Traditional prime brokers have spent decades coordinating financing and collateral for hedge funds trading across different markets. Crypto markets lack this infrastructure. Funds trading CME futures, Hyperliquid perpetuals, and spot Bitcoin must maintain separate collateral pools for each venue, even when all positions form part of the same strategy.
CRX Trade, a Swiss institutional prime brokerage, is attempting to address this by allowing professional traders to manage collateral across crypto exchanges and traditional markets through a single account. Its risk engine monitors positions across a fund's entire portfolio and can attempt to close both sides of a hedge together before an individual exchange forces a liquidation. This approach, called delta-neutral liquidation, aims to prevent the situation where one side of a hedge is closed while the other remains exposed.
However, coordinated risk management has limits. Software cannot force an exchange to process orders during an outage, nor can it guarantee buyers at reasonable prices during volatile markets. Exchanges retain the right to liquidate positions that fail to meet their margin requirements.
The Costs of Capital Efficiency
Loan terms for leveraged Bitcoin positions typically run 30 to 90 days. Lenders can decline to renew loans when they mature, regardless of whether the fund's strategy is profitable. Exchange margin requirements and derivative funding costs can also shift during the loan term, forcing funds to demand additional collateral while borrowers need to repay or refinance.
During market disruptions, funds may need cash at multiple exchanges simultaneously, precisely when transfers become difficult and closing positions becomes expensive.
More efficient collateral coordination can reduce unnecessary liquidations and lower hedging costs. But it also allows funds to support larger positions without committing more of their own capital. The better a fund becomes at putting every dollar to work, the less money it has available for unexpected problems.
The true test of this efficiency will not be how much exposure $1 million can support during calm markets, but how much exposure a fund can safely maintain when lenders, exchanges, and custodians all demand payment simultaneously.