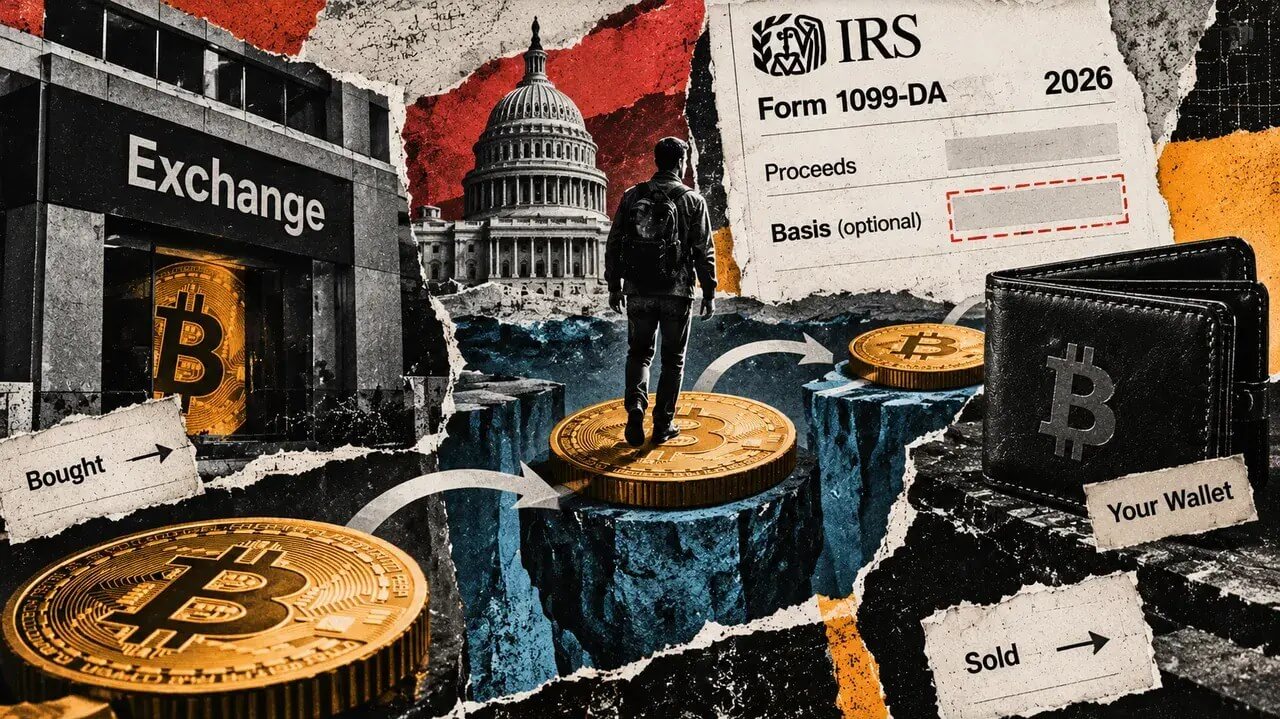
A reporting gap has emerged in US cryptocurrency tax rules for 2026. Bitcoin investors can withdraw coins from an exchange, move them to a personal wallet, return them to the same account, and still fall outside mandatory cost-basis reporting when those coins are eventually sold.
Under the IRS's 2026 Form 1099-DA instructions, covered digital assets must have been acquired after 2025 in a broker's custodial account and held there continuously. Assets bought before 2026 or transferred into the broker from elsewhere are classified as noncovered, meaning basis reporting becomes voluntary rather than mandatory.
This creates a practical divide: brokers remain required to report sale proceeds, but reporting the acquisition cost stays optional for noncovered assets. The distinction matters because calculating capital gains requires connecting the original purchase price to the eventual sale price.
The Three-Path Problem
Consider a simplified example: 0.1 Bitcoin purchased for $5,000 in February 2026 and sold for $7,000 in September, producing a $2,000 gain. The gain calculation remains identical across three custody scenarios—bought and held with one broker, transferred between brokers, or withdrawn to a personal wallet then returned. Yet only the first path triggers mandatory basis reporting under current rules.
The third path reveals the reporting blind spot. Returning coins to an original account does not satisfy the continuous-custody condition required for covered-asset status. A broker's purchase record does not automatically restore basis for coins that left and returned to the account.
Platform Practices Add Complexity
Major exchanges handle the gap differently. Coinbase's current guidance distinguishes its 2025 forms, which report proceeds only, from basis information beginning in 2026 for certain assets. The company instructs customers to retain records from other accounts and wallets.
Kraken's guidance describes a more specific split: customer copies showed estimated basis and gains using first-in-first-out accounting, while what was sent to the IRS was gross proceeds only. Kraken tracks basis for activity within the same account but does not track activity outside it, and treats returning assets as a new deposit without automatically restoring their previous basis.
This distinction creates three separate questions for investors: what the platform displays, what it reports to tax authorities, and what their full transaction history supports.
International Reporting and Blockchain Analytics
International developments add another layer. The OECD's Crypto-Asset Reporting Framework provides for annual exchange of crypto-transaction information between tax authorities. The UK's HMRC, for example, requires user details and transaction summaries, with the first provider report due between January 1 and May 31, 2027, covering calendar 2026.
Blockchain analytics firms are expanding visibility into on-chain activity. Chainalysis estimated more than $457 billion in potentially taxable on-chain activity during 2025, including approximately $112.6 billion attributed to the US. However, these estimates exclude trading, staking, and lending conducted inside centralized exchanges and do not apply certain countries' transaction or income exemptions.
Address tracing can connect asset movements, but a path between addresses does not establish an investor's purchase price, unchanged ownership, or which acquisition lot was sold.
Record-Keeping Requirements Remain
For US investors, a complete gains record requires continuity of information and ownership. The connection between the original purchase and eventual disposal cannot be established by an incoming transfer's date and quantity alone.
The IRS requires investors using specific identification to identify units to their custodial broker by transaction time using its designated identifiers and to retain substantiating records. A spreadsheet choice made later does not substitute for timely identification at the time of sale.
While a blank basis field on a 1099 form cannot be read as a zero-cost basis, investors remain responsible for documenting their actual acquisition costs. Better interoperability among platforms could reduce reconstruction work, but would not change the current rule requiring continuous custody for mandatory reporting.