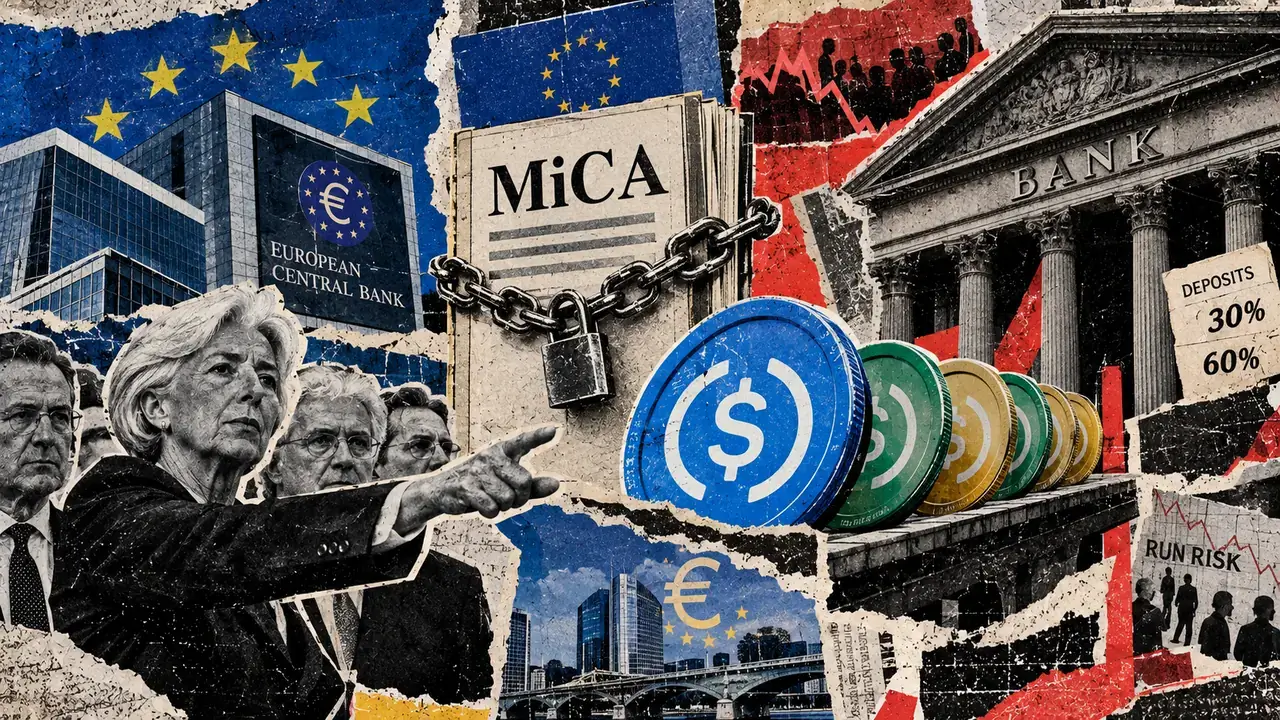
Europe's central banks want to reshape how stablecoin reserves are managed under the Markets in Crypto-Assets Regulation, proposing to replace fixed deposit requirements with liquidity-based safeguards.
The European System of Central Banks has submitted input to the European Commission's ongoing review of MiCA, according to reports in September. The central banks propose removing mandatory minimum deposit allocations with EU credit institutions and instead require that reserves meet liquidity thresholds based on redemption timelines.
Current Framework and Proposed Changes
Under current MiCA rules, issuers of non-significant stablecoins must hold at least 30% of reserves tied to official currencies as deposits with EU banks, with the requirement rising to 60% for significant tokens. The European System of Central Banks wants this fixed minimum eliminated.
The alternative approach would require that at least 20% of reserves for non-significant tokens be available as cash within one working day, with 30% available within five working days. For significant tokens, these thresholds would rise to 40% and 60% respectively. Bank deposits would remain eligible under this framework, but issuers would gain flexibility to allocate reserves across deposits, short-term securities, and repurchase agreements.
Why the Current Rule Creates Risk
Bank deposits give stablecoin issuers immediate cash for redemptions, but they also tie reserve quality to the health of the institutions holding that money. During banking stress in March 2023, Circle held part of USDC's reserves at Silicon Valley Bank. Uncertainty over access to those funds pressured the token's peg, and USDC's market capitalization fell 26% over a month, according to analysis by the European Central Bank.
When stablecoin holders rush to redeem tokens, issuers may withdraw large deposits at once, effectively converting what appeared to be stable funding into volatile wholesale money for the receiving bank. This creates a two-way channel: bank distress can impair token reserves, while token runs can drain bank funding.
How the Maturity-Based Approach Would Work
The reported alternative replaces a location-based rule with a speed-based test. Rather than mandating where reserves must sit, it would specify how quickly the entire reserve pool must produce cash. Eligible assets would include cash, reverse repurchase agreements that can be terminated within the required window, and highly liquid financial instruments already defined under European banking rules.
Under the proposal, issuers would face concentration limits: deposits at a single systemically important bank could not exceed 25% of reserves or 1.5% of that bank's total assets. Highly rated sovereign debt and similar instruments would be capped at 35% of reserves when sourced from a single issuer.
Shifting Risk Rather Than Eliminating It
The change would likely improve issuer economics, as short-term sovereign paper and repo positions may offer better returns than bank deposits. This could shift reserves toward government-debt and funding markets, which carry different risks than concentrated bank exposure.
Heavy redemptions could force securities sales or unwind of repo positions. If stablecoin issuers hold concentrated positions in sovereign or funding markets, stress in one system could propagate to another. Conversely, falling bond prices could weaken reserve values in a declining market.
The European Central Bank has noted that the impact of stablecoin demand for sovereign debt depends on issuer type, asset mix, and the sources of money originally used to purchase the tokens.
Broader Regulatory Framework Remains
Removing the deposit floor would leave other MiCA requirements intact. Issuers would still face authorization, governance, capital, audit, reserve segregation, redemption, and prudential supervision rules.
The European Commission's consultation on the MiCA review runs through September 30, and responses may inform a later legislative proposal. The policy question remains whether Europe can loosen the direct link between stablecoins and bank funding while preserving the liquidity needed for reliable redemptions under stress.