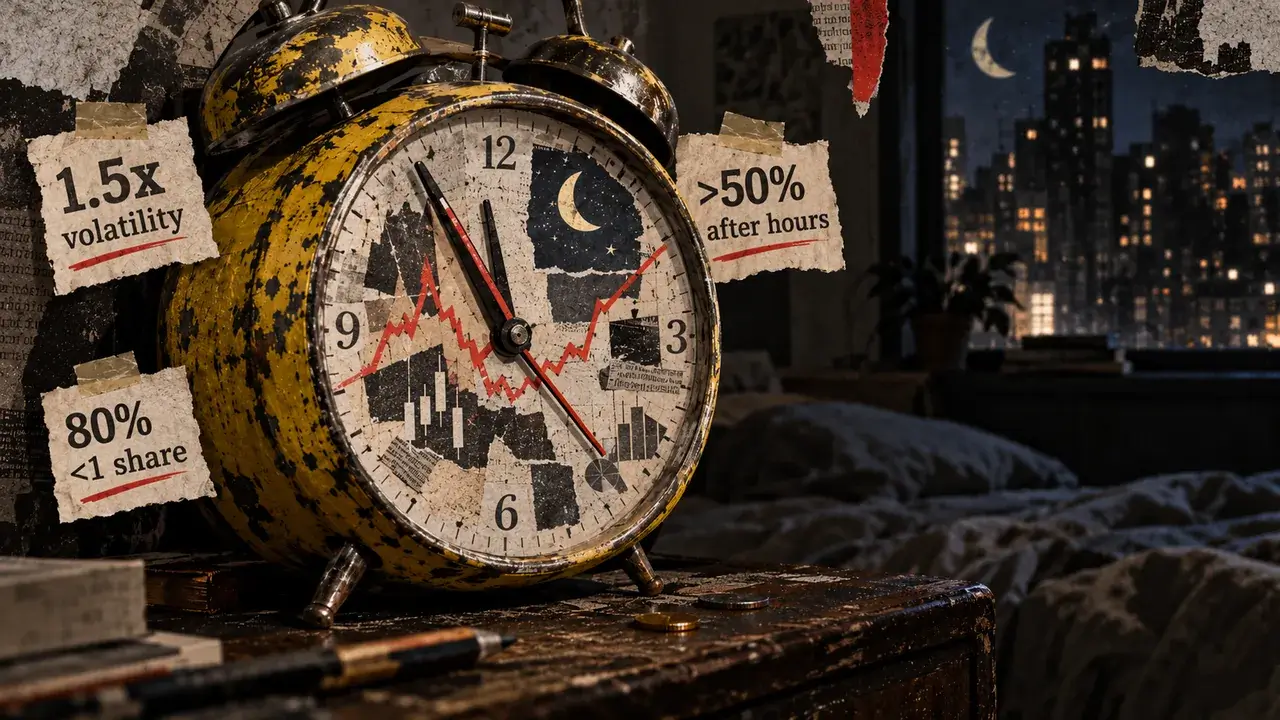
More than half of tokenized US stock trading occurs outside Wall Street's regular operating hours, according to the International Monetary Fund's October Global Financial Stability Report. The IMF examined five actively traded tokenized equity products tracking the S&P 500, Nasdaq, Tesla, Alphabet, and Nvidia across 11 centralized and decentralized trading venues over 365 trading days.
The analysis covered approximately $345 million in tokenized equity market value, representing 15% of the $2.3 billion tokenized equity market as of July 31. Researchers collected more than 2 million five-minute observations of price and trading-volume data.
Trading Patterns and Fractional Investment Demand
The study found that approximately 80% of tokenized equity transactions involved less than one share, suggesting strong demand for fractional investments and continuous market access. Trading activity occurred outside the regular 9:30 a.m. to 4 p.m. Eastern session, including overnight and weekend periods, indicating participation from investors in different time zones seeking to respond to market developments without waiting for US exchanges to reopen.
Overnight Prices Influence Traditional Markets
Overnight tokenized stock prices contained information subsequently reflected in conventional equity markets. Comparing overnight tokenized price movements with traditional securities' performance during the first five minutes of the next US trading session revealed an estimated pass-through ranging from 87% to 99%. However, the analysis does not establish whether on-chain trading causes these price movements; both markets may be responding to the same developments.
Market Quality Concerns
Tokenized equities experienced roughly 50% higher realized volatility than their traditional counterparts, with realized volatility approximately 1.5 times that of traditional equivalents. Fragmented trading venues offered significantly weaker liquidity, with decentralized platforms showing even greater volatility concerns. Small transactions on decentralized exchanges could produce disproportionately large price movements due to limited market depth and market-making activity.
Traditional exchanges remained substantially more liquid than tokenized platforms, with centralized crypto venues performing better than decentralized exchanges. Decentralized venues saw wider and more frequent price deviations, particularly when trading volumes were low.
Systemic Risk and Regulatory Challenges
The IMF estimated that public tokenized real-world assets, excluding repurchase agreements and stablecoins, reached approximately $65 billion by July, compared with roughly $300 trillion in traditional capital-market assets. The Fund said systemic risks remain limited at current adoption levels.
However, broader use of continuous trading and automated settlement could accelerate market stress. Automated collateral management could trigger margin calls and forced liquidations outside conventional trading hours, potentially amplifying selling pressure when liquidity is thin.
The IMF identified legal certainty, regulatory clarity, interoperability between trading networks, and reliable settlement assets as major constraints on further growth. Questions remain over whether tokenized securities provide direct ownership claims or contractual price exposure.
The IMF called for circuit breakers, trading halts, and liquidity safeguards adapted to continuous markets, alongside stronger monitoring of connections between tokenized and traditional finance. Regulators must assess whether existing protections can operate during weekends and overnight trading, when automated liquidations may occur without the liquidity normally available during Wall Street's regular session.