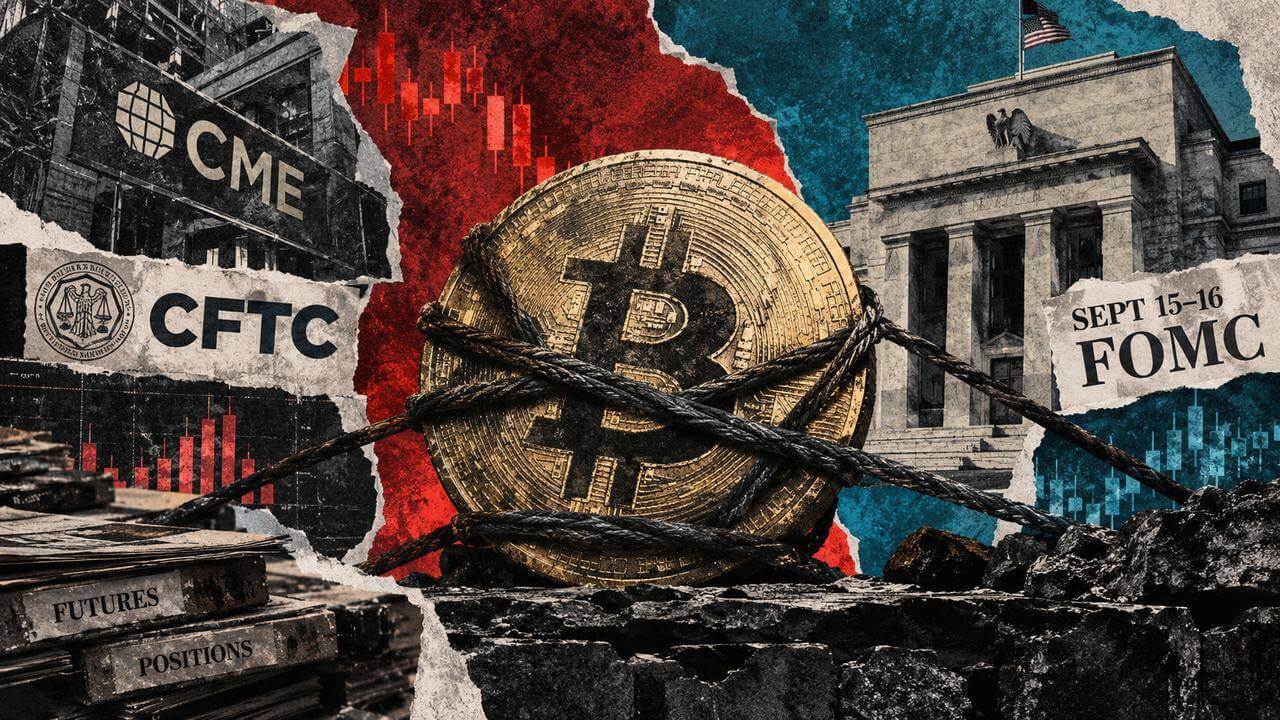
Leveraged funds increased their combined net short position across four regulated Bitcoin futures markets by 1,668 BTC in the week to September 8, according to CFTC futures-only data. The BTC-normalized position widened to 39,876 BTC net short from 38,208 BTC a week earlier.
The calculation covers CME's standard and micro Bitcoin futures contracts along with Coinbase Derivatives' nano and nano perpetual-style contracts, using each market's stated Bitcoin multiplier. CME's five-BTC contract supplied the majority of the shift, with leveraged funds adding 888 short contracts and 616 long contracts, widening the net short by 1,360 BTC. That represented 81.5% of the combined weekly change.
Across all four contracts, short exposure increased by 4,965 BTC while long exposure rose by 3,296 BTC. The simultaneous growth in both directions suggests positioning more complex than a single directional bet.
Intent Remains Unclear
The CFTC category of leveraged funds includes hedge funds, commodity trading advisers, commodity pool operators, and other money managers. Their strategies can encompass outright positions as well as arbitrage and hedging within and across markets.
A short futures position can hedge a long spot or spot ETF holding, a structure known as a basis trade designed to capture the spread between futures and spot exposure. Public CFTC data omits links to offsetting positions, leaving directional positioning, basis hedging, or a mixture of both as possible explanations.
The expanded short exposure was in place ahead of the September 15–16 FOMC meeting. CFTC reports typically publish Friday at 3:30 p.m. Eastern using the preceding Tuesday's positions, creating a four-day gap between publication and the Fed meeting. While the 1,669 BTC increase shows that leveraged-fund futures shorts rebuilt before the event, trade-level intent remains hidden, leaving the data short of proof that traders made an unhedged wager on a post-Fed Bitcoin decline.