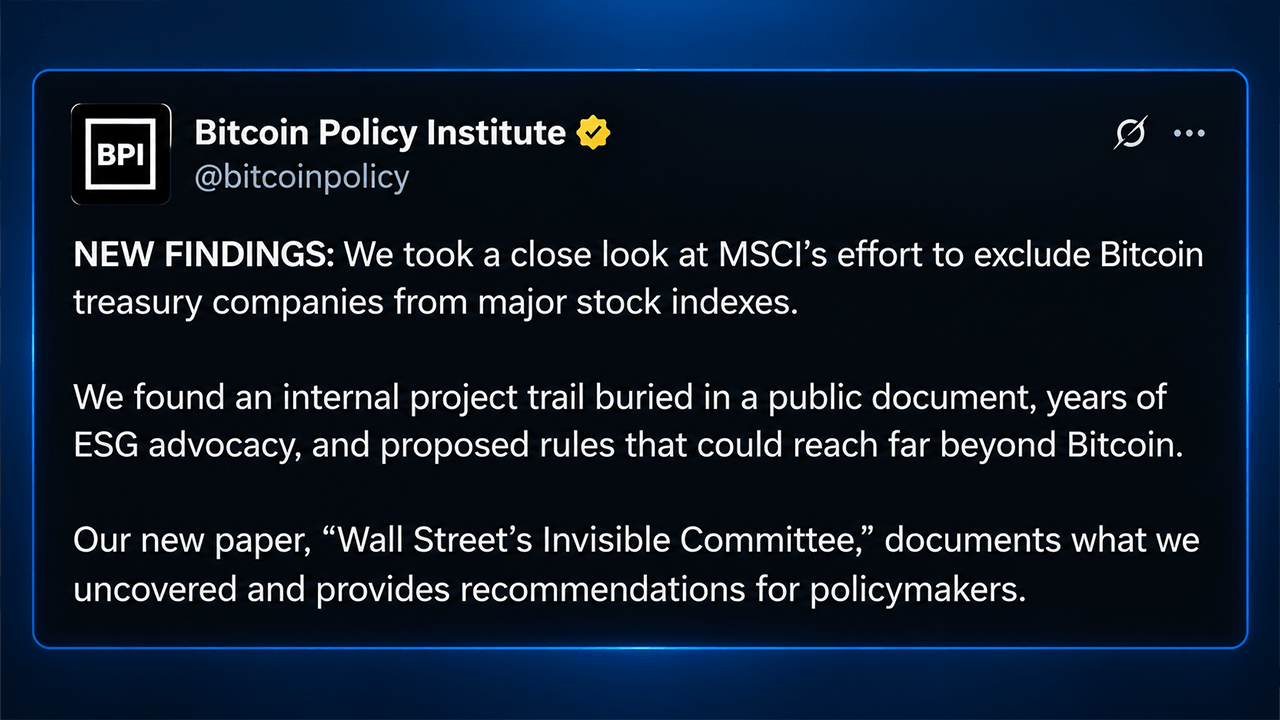
A recent paper published by the Washington, D.C.-based think tank Bitcoin Policy Institute highlights the influence of private index providers on global stock trades. Written by Executive Director Conner Brown, the 23-page report analyzes MSCI's proposed index rules and their potential impact on companies that hold significant non-traditional assets, including bitcoin treasuries and physical commodities.
According to the paper, MSCI's simulated index deletions include firms such as Strategy, Metaplanet, and uranium holder Yellow Cake. Previous estimates from JPMorgan indicated that MSCI-linked fund selling alone could reach $2.8 billion for Strategy if removed from major indexes, with potential totals climbing higher if other providers followed suit.
The Shift to Operating Assets
Earlier proposals from MSCI focused on excluding companies whose digital assets represented at least 50% of total assets. After shelving that specific digital asset approach, MSCI introduced a broader test in August centered on whether a company maintains sufficient "operating assets." Under this framework, companies failing an initial screen face additional financial tests that can lead to index exclusion.
The Bitcoin Policy Institute paper raises concerns over the classification of "operating assets," noting that the category is not standardized under U.S. GAAP or IFRS. This leaves index providers to classify items ranging from cash and mineral rights to strategic holdings. The paper specifically cites Strategy's accounting figures, arguing that reaching MSCI's simulated exclusion results requires analytical reclassifications not disclosed in the consultation.
Broader Market Implications
The paper illustrates how the proposed methodology could extend beyond bitcoin treasury firms to other capital-intensive businesses. By testing the rules on companies like Yellow Cake, AST Spacemobile, and Lithium Americas—which is developing a lithium project in Nevada—the analysis suggests that heavy upfront construction costs and reliance on outside financing before revenue generation could trigger index flags.
MSCI is expected to reach a decision on or before October 16, with any adopted changes scheduled for implementation during its November index review around December 1.