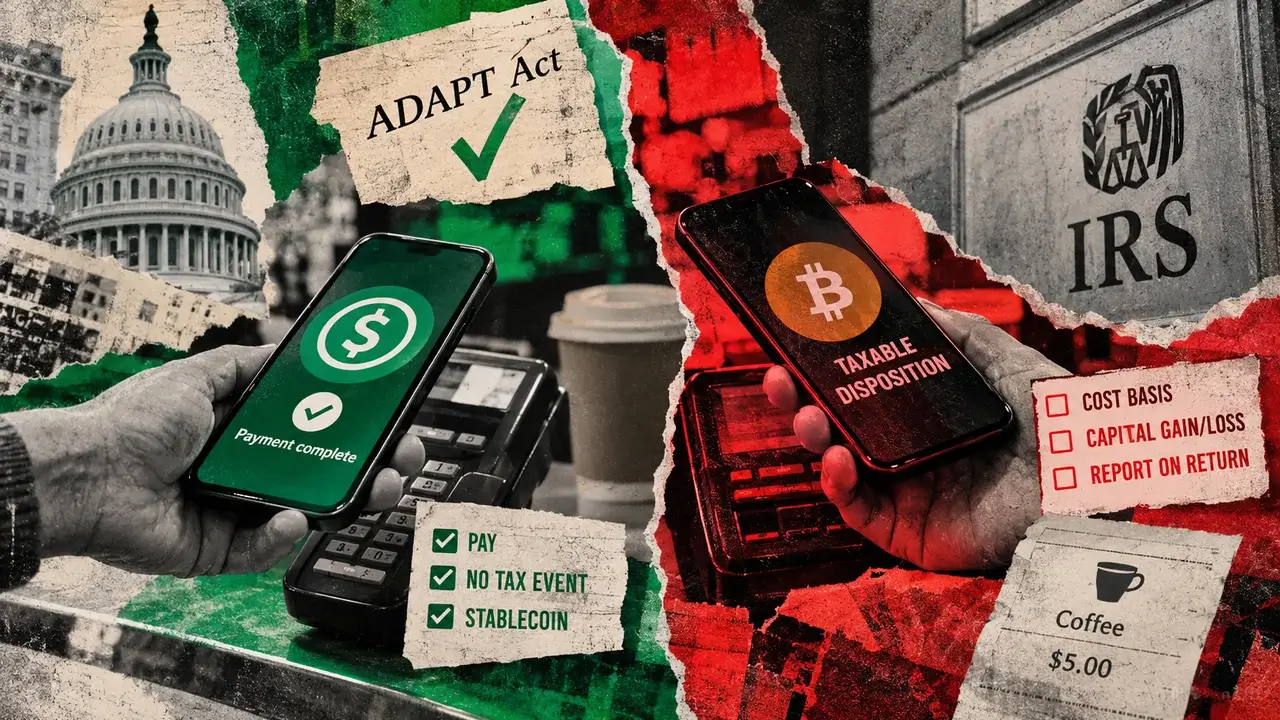
A coffee purchased with a qualifying dollar stablecoin would avoid capital gains recognition under the ADAPT Act released Sept. 30 by Sen. Steve Daines, while the same coffee bought with Bitcoin would remain subject to cost-basis calculations and capital gain or loss reporting.
The 56-page bill, titled the Aligning Digital Assets with Principles of Taxation Act, lists Sens. Cynthia Lummis, Bernie Moreno, and Tim Scott as cosponsors. Currently, the IRS treats any payment made with digital assets as a taxable disposition requiring holders to calculate and report gains or losses.
Stablecoin Relief Under the Proposal
New section 1034 of the tax code would treat dispositions of covered payment stablecoins to purchase products or services as nonrecognition events. The relief covers gain or loss on the token itself, though sales taxes and other purchase obligations remain in place.
To qualify, a stablecoin must be a qualified U.S. dollar stablecoin issued by a permitted payment stablecoin issuer under the GENIUS Act. Foreign issuers can qualify through OCC registration or a Treasury finding that their home regulatory regime is comparable. Taxpayers must have acquired qualifying tokens at a price within 3 percent of $1.00.
Treasury would publish a quarterly report listing each qualified stablecoin actively traded within 3 percent of $1.00. Traders, brokers, and dealers in qualified stablecoins are excluded from the relief, as are taxpayers using a functional currency other than the dollar. The stablecoin provision would apply to transactions starting Jan. 1, 2027.
Limited Relief for Bitcoin and Other Digital Assets
Bitcoin payments at checkout would remain subject to taxable disposition treatment. However, the bill includes a narrower provision under new section 1044 allowing digital assets disposed of to pay transaction fees to escape gain-or-loss recognition when the aggregate value is $10 or less. Base, gas, and priority fees count as costs. This fee exception also takes effect Jan. 1, 2027 and excludes traders, brokers, dealers, and those who initiated more than 5,000 digital asset transactions in the prior year.
The bill also exempts qualified dollar stablecoins from wash-sale and constructive-sale rules that would apply to other digital assets.
Previous Legislative Approaches
Earlier proposals used monetary thresholds to reduce tax friction. Sen. Ted Budd's S.4171 would have required both transaction value and recognized gain or loss to be $200 or less. Lummis's S.2207 set a $300 ceiling on transaction value and recognized loss, ending exclusions once qualifying annual gains exceed $5,000. The House PARITY Act proposed a $200 threshold for stablecoin transactions.
A separate House proposal, H.R.10357, introduced Sept. 14, includes distinct stablecoin redemption-value accounting and qualifying $10 fee relief mechanisms. The Ways and Means Committee approved the House bill 38-5 on Sept. 16.
Current Status and Implementation
These remain proposals and current IRS treatment remains in force. Treasury would set the mechanics, including the quarterly list, recordkeeping, and broker reporting rules. Stablecoin qualification would follow issuer approvals under the GENIUS Act.