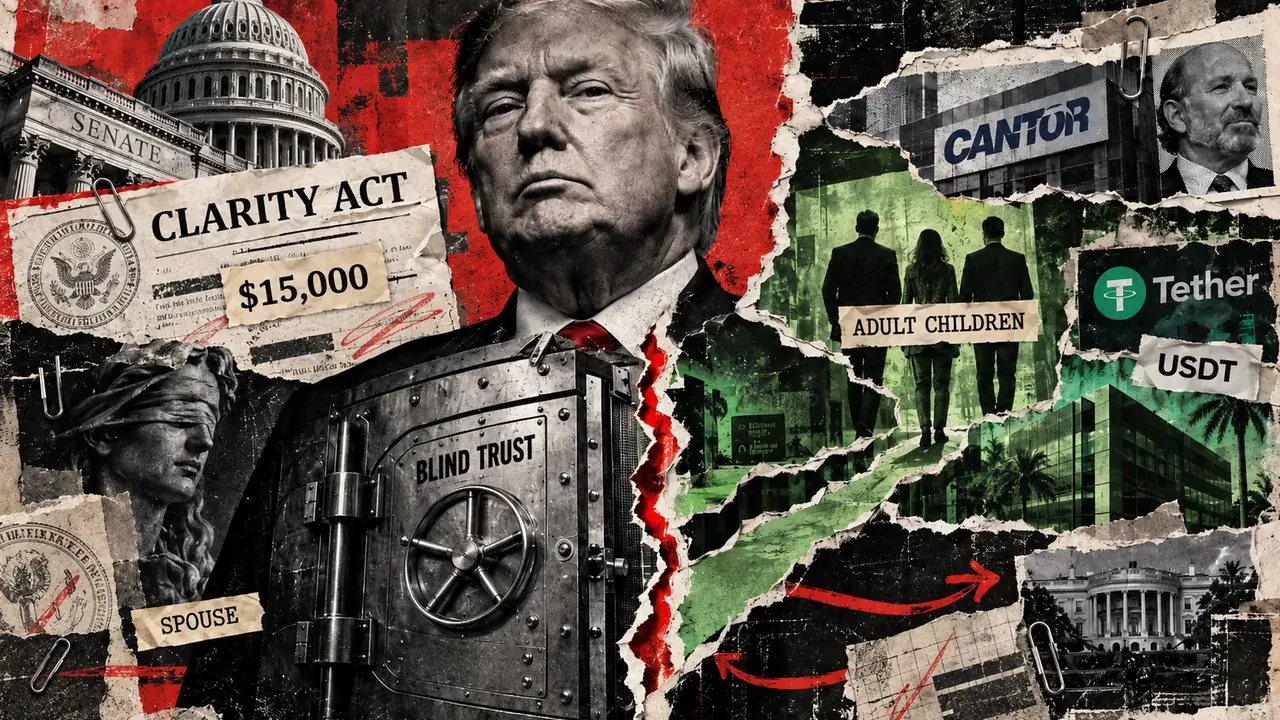
The Senate's final draft of the CLARITY Act proposed a specific threshold for crypto-related conflict-of-interest rules before the bill failed to advance on September 15. Under the proposal, senior federal officials and their spouses holding equity worth at least $15,000 in businesses that issue or sponsor digital assets would have been required to sell that interest or place it into a qualified blind trust. Adult children would have been exempt from this requirement.
The bill was primarily intended to establish regulatory authority over crypto markets, but negotiations expanded to address how officials' crypto holdings should be managed. Republicans characterized the final draft as incorporating most of a bipartisan ethics proposal and dozens of changes requested by Democrats, while some Democrats argued the protections remained insufficient.
The Scope of the Proposed Rule
The ethics provision targeted a narrower category than a general ban on politicians holding cryptocurrency. Ownership of Bitcoin or other digital assets would not automatically have triggered the requirement. Instead, the rule focused on equity interests in businesses or subsidiaries whose largest revenue source in any of the preceding three calendar years was issuing or sponsoring digital assets, excluding tokenized traditional assets. Officials would also have been restricted from issuing or sponsoring digital assets for compensation.
Coverage would have extended to the president, vice president, senior executive officials, members of Congress, and other federal officeholders already subject to public financial-disclosure rules. Spouses would have been included, but adult children would not.
Qualified Blind Trusts Versus Family Transfers
A qualified blind trust under federal ethics rules operates under strict standards that differ substantially from simply transferring assets to family members. A qualified blind trust requires an independent trustee and limits the official's knowledge of and control over investments. Federal ethics guidance generally treats holdings as known until the trustee disposes of them or they fall below relevant thresholds.
Under the CLARITY draft, the trustee's actions and those of businesses held in the trust would not be attributed to the official, making the arrangement stronger than disclosure alone. This contrasts with transferring a family company to adult children, which removes the official's control while deliberately keeping ownership within the family.
Real-World Examples
Commerce Secretary Howard Lutnick, who entered the Trump administration in February 2025, illustrates the distinction. Lutnick previously ran Cantor Fitzgerald, a major Wall Street trading and investment firm that became deeply embedded in crypto through its relationship with Tether, the company behind USDT, the world's largest stablecoin. Cantor has held billions of dollars in Treasuries for Tether and remains involved in its U.S. business as a reserve custodian and preferred primary dealer for Tether's regulated U.S. stablecoin.
When Lutnick entered government, he transferred his ownership through trusts benefiting his adult children. His son Brandon now runs the company and controls the trusts holding voting interests. SEC filings show that after the October 2025 transfer, Lutnick no longer held beneficial ownership of the securities tied to that control structure. Economically, however, the family remains heavily exposed to the same business.
The Political Divide
The exclusion of adult children from the proposed rule became a key point of disagreement. Under Trump's latest certified financial disclosure, more than $1.4 billion in 2025 income came from crypto ventures, according to Reuters, with most connected to World Liberty Financial and Trump meme coin business. Under the Senate proposal, a qualifying interest still owned by Trump himself could have required divestment or a blind trust, with the same rule applying to a spouse. Ownership held independently by adult children would have fallen outside the requirement.
Federal conflict law has traditionally drawn the line relatively close to the official. Financial interests of a spouse or minor child are generally attributed to an executive-branch employee, while an independent adult child's interests typically are not. This approach prevents the law from treating every financially independent adult child as an extension of a government official.
The Unresolved Problem
Crypto has made the traditional Washington issue of family wealth harder to contain. Government policy can rapidly change the value and viability of privately held token businesses. Stablecoin regulation, banking rules affecting access to dollars, and securities law determining whether a token business can operate in the U.S. all directly affect crypto companies.
Congress can require a president or Cabinet secretary to sell an asset or use a blind trust, but it has not settled how far such restrictions should extend once a business passes to the next generation.