North Dakota banks and credit unions now have a new settlement route on Solana's blockchain. Fiserv, a banking technology provider, has launched Roughrider Coin in production, marking the first live use case for its digital asset platform.
Roughrider is an interbank payment token overseen by the Bank of North Dakota (BND). More than 90 North Dakota banks and credit unions are participating in the rollout, according to Fiserv's announcement made on October 1.
How Roughrider Works
Participating institutions access Roughrider through Commercial Center, Fiserv's existing online banking system used for traditional interbank transfers. Initiation, approval, and settlement operate through the same channels banks currently use for ACH and wire transfers, allowing staff to work within familiar systems.
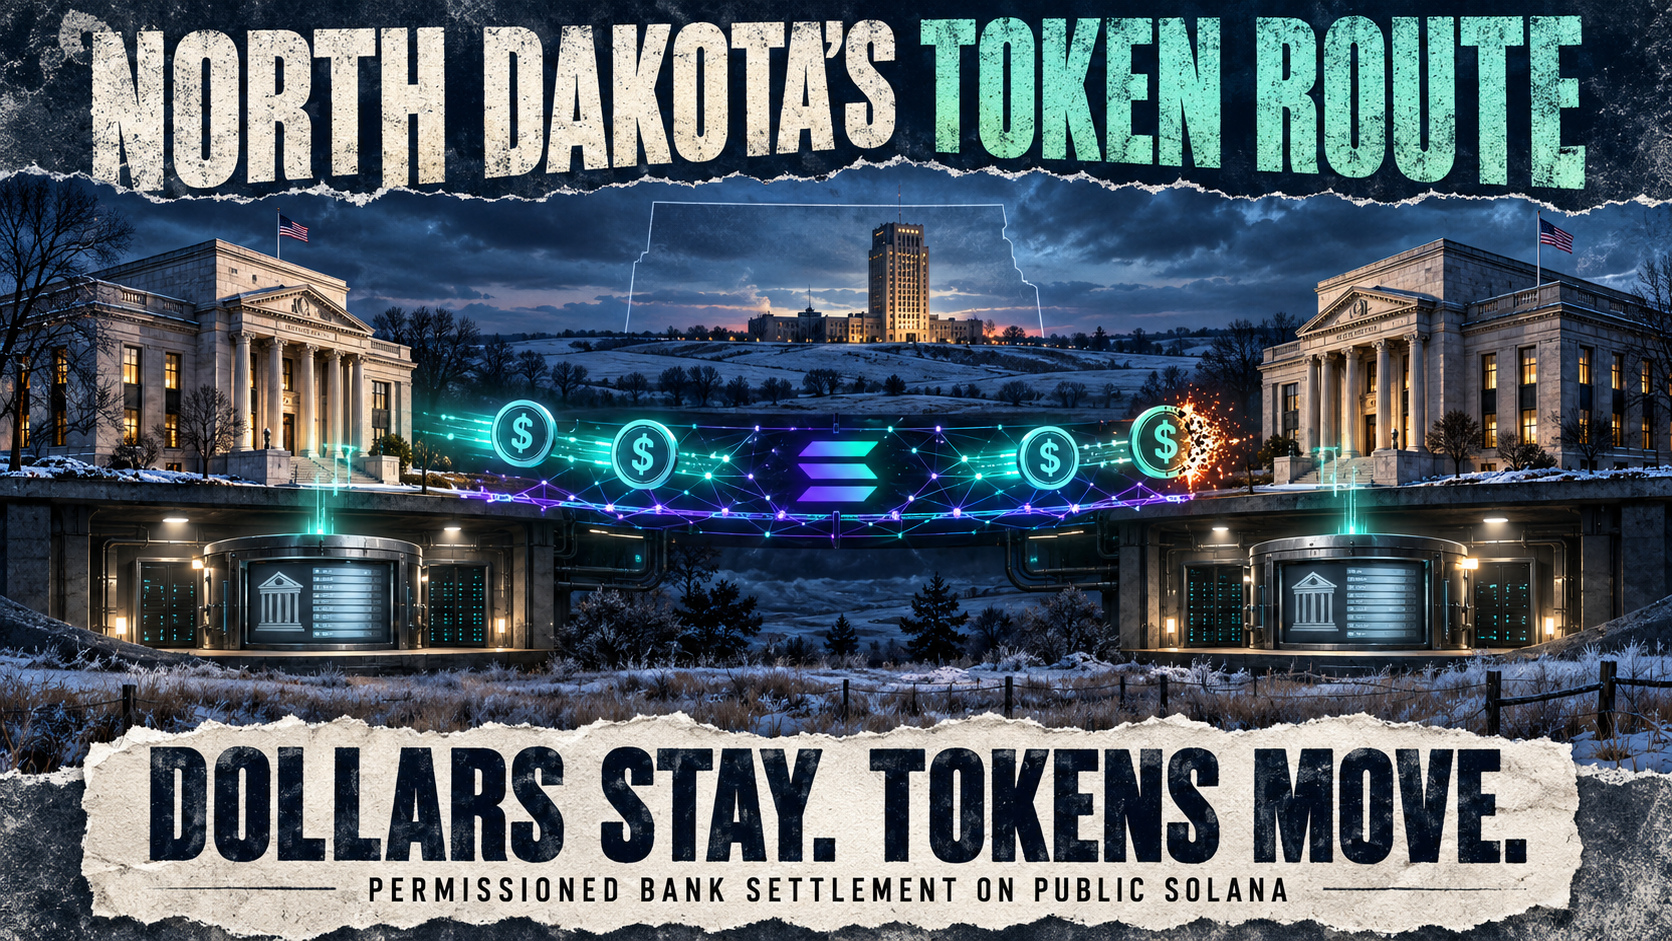
VersaBank USA National Association issues Roughrider under BND governance oversight. The token operates on Solana's public blockchain as a permissioned asset, with access restricted to financial institutions. BND describes the system as dollar-backed, with each token holding one-to-one US dollar backing.
Minting occurs only after a confirmed transfer from an institution's operating account into a designated account. When tokens arrive at the receiving institution's wallet, they are automatically burned through a smart-contract instruction, designed to keep token balances low. Dollars remain in bank accounts while matching tokens move and burn on Solana.
Design and Features
BND manages daily netting of account movements across custody accounts and a concentration account held at BND itself. Token settlement and banking-account reconciliation are separate components of the design.
Fiserv assigns VersaBank responsibility for minting, burning, custody, and reserve management. The system uses Fireblocks-secured wallets and leverages Solana's Token-2022 extensions, which provide freeze and clawback capabilities.
Positioning and Use Cases
BND positions Roughrider for treasury transfers and loan payoff scenarios, offering near-instant settlement around the clock and lower costs compared to wire transfers. However, launch materials do not disclose measured realized savings or performance-testing methodology.
For community banks, Roughrider represents an additional settlement option embedded within existing banking workflows. The extent to which participating institutions adopt it for routine interbank business remains to be seen.