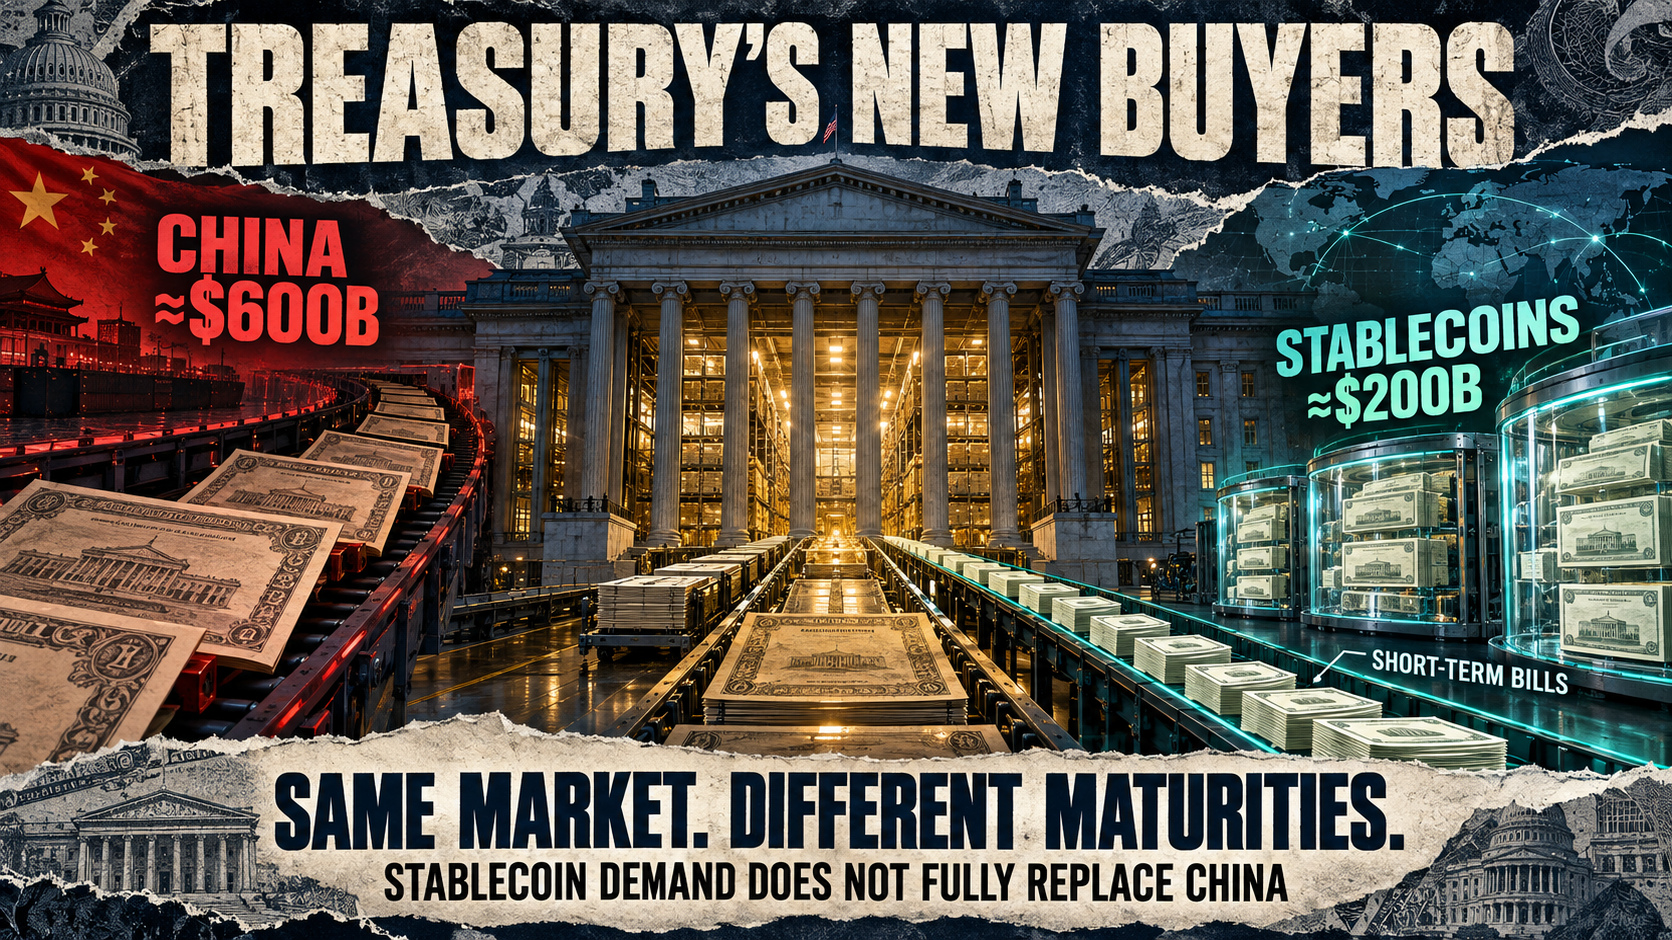
Stablecoin issuers are emerging as a new source of demand for US government debt as foreign official holdings decline. According to researchers at the Federal Reserve Bank of San Francisco, Tether and Circle have increased their Treasury securities and repurchase-agreement holdings by approximately $200 billion over the past five years.
This increase is equivalent to more than 40% of the decline in China’s Treasury holdings over the same period. The shift is altering the investor base underpinning the largest government bond market in the world, with stablecoin issuers' Treasury holdings rising more than tenfold over five years alongside expanding demand for dollar-linked digital tokens.
Foreign investors held more than half of outstanding Treasury securities around 2008, but that share dropped to roughly 30% by early 2026. Within that segment, foreign governments fell even more sharply in relative importance, accounting for just above 40% of foreign Treasury demand by early 2026, compared to nearly all of it during their peak in the 1970s. China's Treasury holdings peaked in late 2013 and fell by more than half by mid-2026 as Beijing diversified its reserve assets.
As official foreign demand weakens, private investors have taken a larger role in Treasury financing. Stablecoin issuers operate with business models requiring large pools of liquid dollar assets to back tokens that customers can redeem at par. As of mid-August, Tether's USDT and Circle's USDC accounted for over 80% of the stablecoin market capitalization, holding substantial short-term Treasury securities alongside cash, bank deposits, and repos to meet redemption demands.
Since 2023, stablecoin issuers have added more short-term Treasury holdings than Japan, the largest foreign holder of US government debt. However, analysts note a maturity gap between these two groups. China's reductions have been concentrated largely in longer-dated US debt, while stablecoin issuers predominantly purchase Treasury bills and other highly liquid, short-maturity assets.
Regulatory frameworks are also reinforcing stablecoin preferences for short-term maturities. The GENIUS Act, adopted in 2025, established a federal framework requiring approved US payment stablecoin issuers to fully back outstanding tokens with eligible liquid reserves. Proposed implementing rules include Treasury bills, notes, and bonds with remaining maturities of 93 days or less, alongside cash and bank deposits.
The San Francisco Fed noted that continued global adoption for cross-border payments and dollar-denominated stores of value could extend the industry's recent growth, potentially lifting stablecoin Treasury holdings toward $400 billion by 2030, though researchers cautioned that the estimate carries substantial uncertainty due to potential regulatory, competitive, and technological shifts.