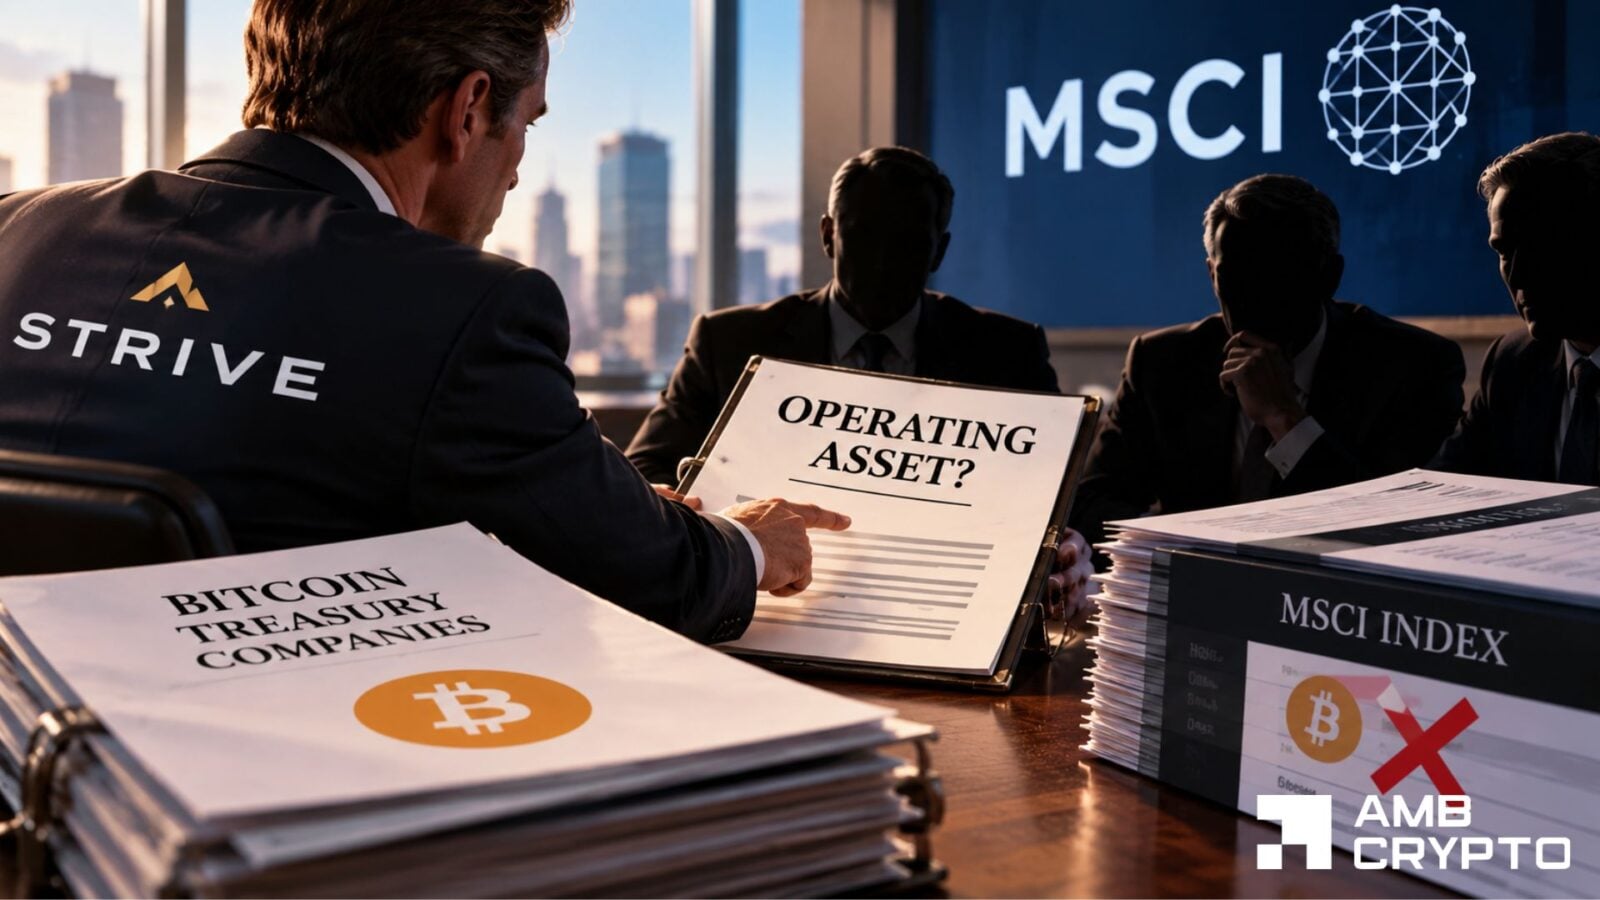
Strive, identified as the fifth-largest Bitcoin treasury, has submitted formal feedback opposing MSCI's proposal to exclude cryptocurrency treasuries from the global index.
MSCI's 2026 framework would remove companies that primarily hold crypto assets, treating them as non-operating investment vehicles rather than operating companies. Strive acknowledged that this approach represents a refinement from the 2025 proposal, which directly targeted crypto treasuries for exclusion.
The Core Dispute
At the center of the disagreement is how to classify companies that hold Bitcoin reserves while generating returns through other financial activities. MSCI proposes excluding firms that buy and hold assets passively. Strive argues the classification should account for companies offering digital credit products backed by Bitcoin reserves.
According to Strive's submission, companies issuing digital credit products backed by Bitcoin reserves operate similarly to traditional financial institutions. These firms apply continuing financial and risk-management processes to balance sheet assets and produce differentiated financial claims with specific payment and risk characteristics tied to the underlying assets.
Strive noted it manages over $2 billion in Bitcoin reserves and has sold portions of its holdings when necessary to maintain liquidity and support ongoing obligations.
Industry Support
TD Securities made a similar argument in its own feedback, contending that the primary product offered by such companies is not Bitcoin itself but differentiated forms of Bitcoin-backed exposure tailored to investor preferences for risk, duration, leverage, yield, and liquidity. This characterizes the activity as corporate rather than passive.
MSCI's Timeline
MSCI opened a feedback period for the proposal, which was set to close by the end of September. The index provider plans to announce its final decision in mid-October, with index rebalancing scheduled for November if the changes are adopted.
Strive has requested that MSCI define what qualifies as an "operating asset" and provide a "future qualification path" allowing firms to make adjustments if needed to meet revised criteria.