Understanding the Layered Structure
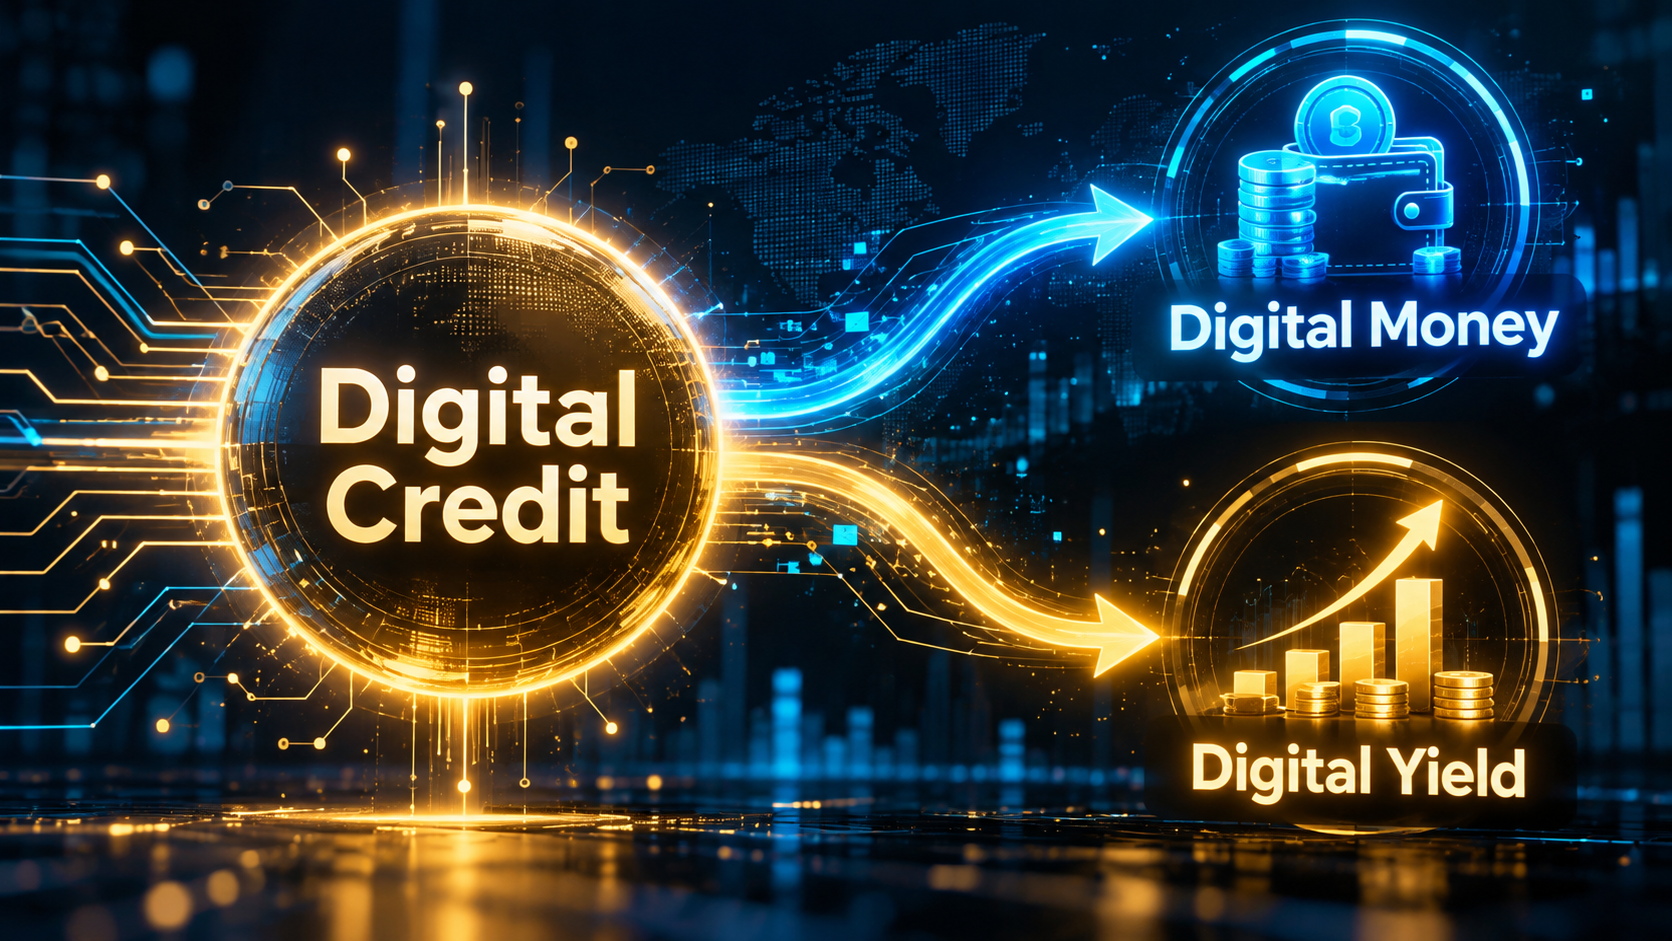
Digital Credit refers to credit-like instruments issued by corporations holding significant Bitcoin. Digital Money and Digital Yield are products built on top of this Digital Credit, forming what is described as a three-layer ecosystem above Bitcoin itself.
Digital Money is characterized as holding a stable fiat-denominated value derived from Digital Credit. Digital Yield concentrates and amplifies the returns of Digital Credit. Both exist as Layer 3 products above Layer 2 Digital Credit.
Debt-Based Tranching Structures
The debt-based tranching approach uses digital credit as base collateral. A junior tranche functions as leveraged long exposure to digital credit, while a senior tranche receives principal protection funded by the junior tranche's permanent capital. This structure currently dominates the market.
UTXO Management's Preferred Income Strategies LP exemplifies this model with dual share classes. Junior shareholders hold leveraged exposure to an underlying digital credit portfolio, while senior shareholders receive principal protection with a stated 7.5% annual yield, provided the portfolio value does not fall below the seniors' invested capital.
This tranching structure mirrors the capital structures used by digital credit issuers themselves, which raise senior-level capital while common equity absorbs junior-level risk. The same principle applies whenever borrowed money is invested into digital credit, creating a leveraged long party and a principal-protected counterparty.
Constraints on Debt-Based Models
A fundamental limitation exists: these structures require persistent demand for leveraged long positions to sustain senior principal protection. Without willing junior capital providers, the system cannot scale indefinitely.
Market observations suggest a shortage of investors willing to hold junior positions relative to those seeking senior positions. Additionally, tranched structures create zero-sum dynamics where gains to seniors equal losses to juniors, constraining the yield seniors can demand before juniors withdraw.
Full-Reserve Spendable Balance Structures
An alternative approach involves holding digital credit in a balance sheet and making it directly spendable. This could involve mixing digital credit with more stable short-duration instruments to moderate volatility while capturing higher yields.
A softer implementation exists with services like Castle, where businesses hold reserves in digital credit instruments, liquidate them on demand for cash, and use proceeds for operating expenses through standard securities settlement processes.
Regulatory Obstacles for Spendable Balances
The primary hurdle for spendable balance structures is regulatory acceptance. The debate over stablecoin regulation and yield-bearing deposit products has created significant resistance from traditional financial institutions viewing such products as competitive threats to bank deposits.
Simpler structures without peer-to-peer transferability face fewer obstacles. OranjeBTC launched a Digital Credit ETF in Brazil holding digital credit without making fund interests directly transferable, even incorporating currency hedging to deliver yields in Brazilian Real.
Future Outlook
Existing regulatory parameters and market developments suggest debt-based tranching solutions will likely see greater near-term activity. Multiple variations of both structural approaches continue to emerge, with their respective advantages and limitations shaping market evolution.