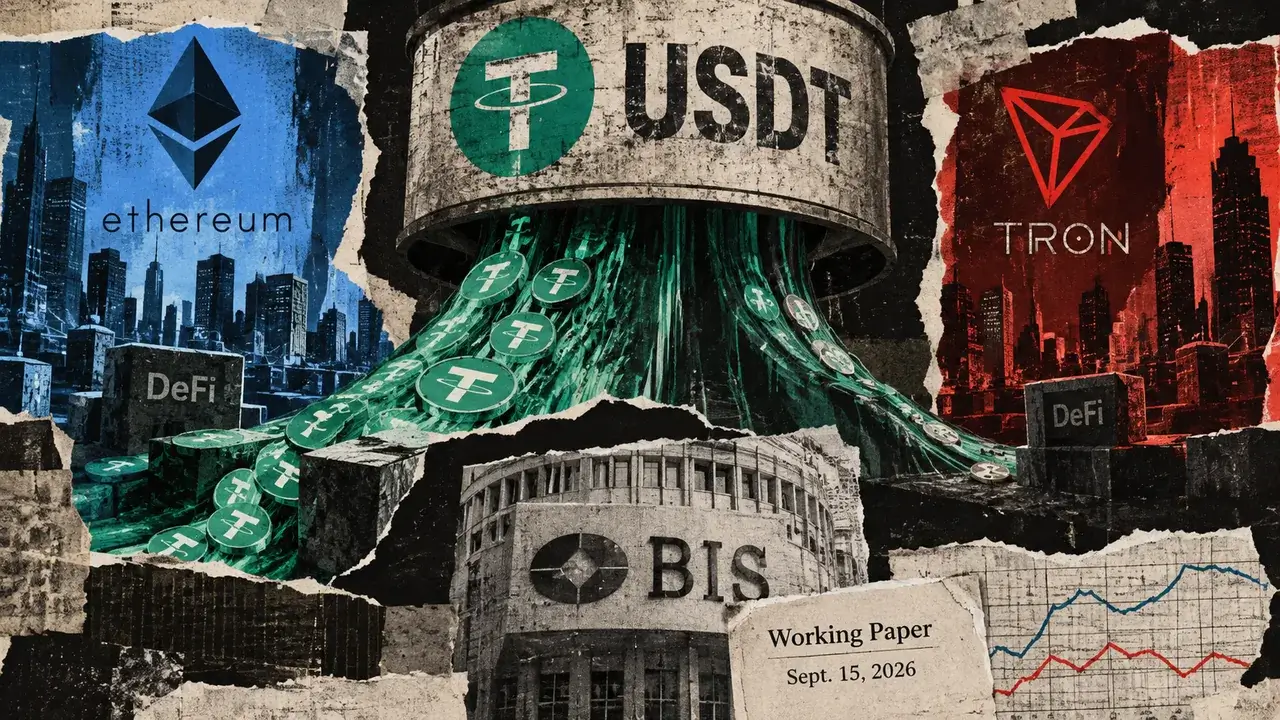
More USDT was issued without a sustained rise in balances held by smart-contract accounts on Ethereum, according to a Bank for International Settlements working paper published in September 2026. On Tron, those accounts held approximately 1% of USDT through most of the study's historical series.
The findings challenge the assumption that a larger stablecoin supply automatically means more capital has entered decentralized finance.
Ethereum's Declining Share
On Ethereum, smart-contract accounts held more than 20% of the network's USDT during parts of 2021 and 2022. Their share remained around 15% to 20% until late 2024, then declined to roughly 10% to 15% as issuance expanded.
The decline represents a change in the proportion of tokens in contracts rather than an absolute decrease in contract holdings. The issuance growth did not bring a sustained increase in contract holdings. Instead, newly issued tokens accumulated outside contracts even as amounts held in contracts remained near earlier levels.
Absolute Balances and Measurement Limitations
Figure 10 of the study places Ethereum contract-held USDT at roughly $10 billion to $15 billion toward the end of its plotted period, and Tron's at around $1 billion or less. Ethereum's dollar balance fluctuated in the low tens of billions while the share shrank; on Tron, contract balances remained a small slice of a much larger supply.
The BIS paper tracks where tokens sit, not why every holder owns them. Its holder-balance chart stops before 2026 on its date axis, so percentages cannot be read as current measurements. That timing matters as current dashboards continue to show large USDT balances on both networks.
Methodology and Its Constraints
The researchers reconstructed USDT holdings from Ethereum and Tron transfer event logs, identifying smart-contract accounts from contract deployments and classifying other addresses as externally owned accounts. This approach differs from protocol-level total value locked measures, which can count the same tokens multiple times across applications.
However, account type remains an imperfect guide to economic use. A smart contract may hold USDT for a bridge, wrapper, or custodian rather than a DeFi lending or trading strategy. An externally owned address may be used for payments, savings, remittances, or exchange custody. Tron's roughly 1% contract-held share does not show that the remaining tokens were spent as payments, nor does Ethereum's falling share prove that DeFi use contracted.
Rising USDT totals, by themselves, establish neither more DeFi deployment nor more payments use, and they say nothing about demand for ETH or TRX.