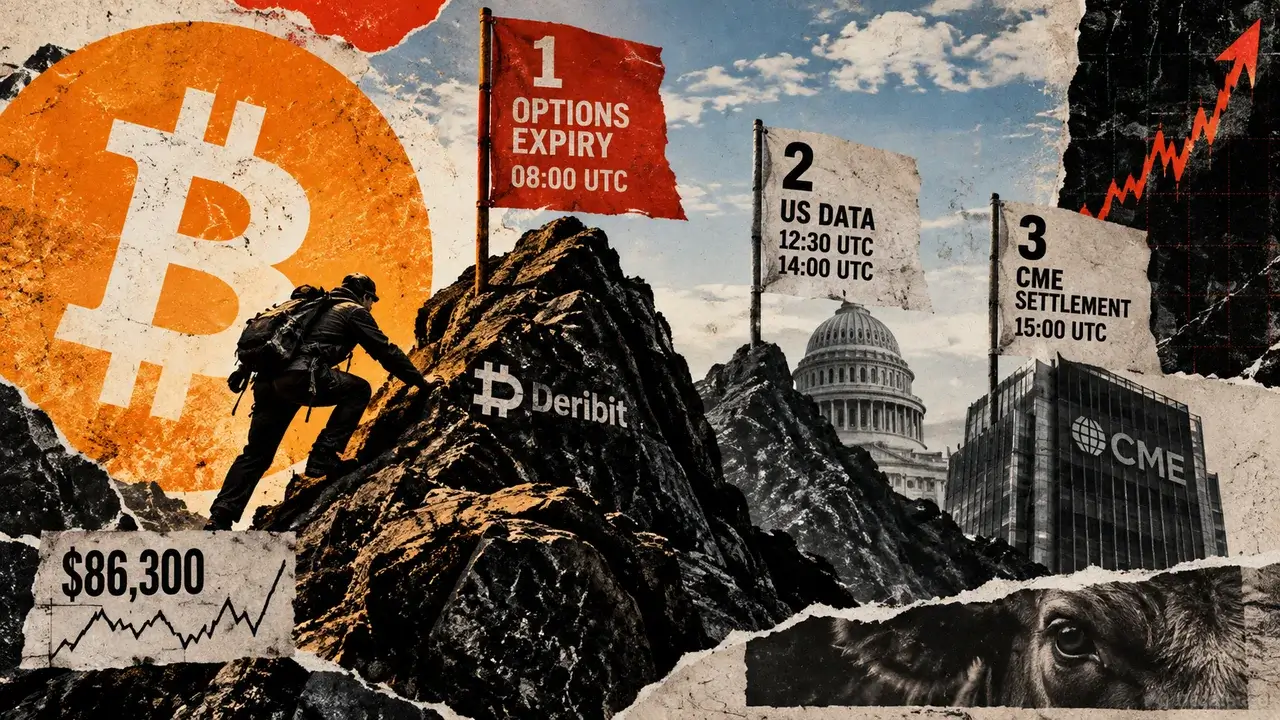
Bitcoin trades near $86,300 heading into a consequential Friday that stacks three separate market events into a single trading day. Deribit will settle roughly $16 billion in notional value of Bitcoin options at 08:00 UTC on September 25, with calls accounting for approximately $9.6 billion and puts for $6.4 billion of that open interest.
The options expiry represents the second phase of a two-part September quarterly expiration cycle. BlackRock's iShares Bitcoin Trust options expired the previous week in what was described as the fund's largest single expiration on record. Bitcoin's rally through $80,000 pushed many of those calls into the money, prompting dealers to purchase IBIT shares for hedging purposes. As demand grew large enough, new IBIT shares pulled spot Bitcoin into the fund through authorized participants.
Technical analysis of the Deribit book using gamma models places the largest call wall at $95,000 and the largest put wall at $60,000. The zero-gamma level sits near $71,000, a price point where dealer hedging behavior shifts from stabilizing to amplifying market moves. With Bitcoin currently trading in the $86,000 zone, the market sits comfortably in the stabilizing zone according to these models.
Options markets are pricing a moderate expected move. Deribit's DVOL index stood at 38.1 on September 22, classified as very low by five-year historical standards. At-the-money implied volatility sat at 38.1%, with skew near neutral. A one-standard-deviation move through Friday calculates to approximately $2,720, or 3.15%, establishing a rough band between $83,600 and $89,100.
Three market events follow the Deribit settlement within seven hours. US durable goods orders arrive at 12:30 UTC, four and a half hours after settlement. The University of Michigan's final September consumer sentiment reading, which includes inflation expectations, lands at 14:00 UTC. CME's September Bitcoin futures settle at 15:00 UTC. The Federal Reserve raised its target rate range to 3.75% to 4.00% on September 16, making both economic data points relevant to rate-sensitive assets.
Historical research published in Finance Research Letters identified intraday Bitcoin price reversals around Deribit expirations, with the effect strongest when at-the-money open interest ran high and estimated gamma exposure was negative. A sharp move that reverses within two hours of settlement would fit that documented pattern.
Recent spot Bitcoin ETF flows have supported the rally. US spot Bitcoin ETFs took in $159.5 million on September 17, $433 million on September 18, and $999 million on September 21. Monday's rally included approximately $647.9 million in short liquidations out of $746.6 million in total liquidations over 24 hours, while aggregate crypto open interest climbed 7.59% to $156 billion.
The bull case has Bitcoin climbing toward $90,000 before settlement while ETF inflows continue and traders roll expiring calls into October and December contracts. Price holding through the durable goods, sentiment, and CME events would allow the $85,000 and $100,000 call blocks to become active on subsequent Deribit books.
The bear case sees Bitcoin stalling between $88,000 and $90,000 as ETF flows slow and strength built into the expiry fades once the book settles. A firmer-than-expected durable goods or inflation-expectations reading hitting a market carrying fewer hedges could drive Bitcoin toward the lower edge of the implied band near $83,600, with $80,000 as the next level beneath it.