Bitcoin experienced a sharp but limited price decline following a major security breach at Binance on Friday morning. The asset dropped approximately $4,000, falling from over $80,000 to $76,100, yet avoided the catastrophic collapse that characterized some previous exchange failures in the industry.
Binance reported that approximately $6.3 billion in cryptocurrency was stolen from compromised hot wallets. The exchange stated that roughly $3 billion was subsequently frozen on-chain by Binance and other partners, while the company committed to covering the entire loss using its Secure Asset Fund for Users (SAFU) and corporate treasury. User balances remained fully protected.
Former Binance CEO Changpeng Zhao offered context for bitcoin's relatively contained market reaction. He argued that while the $6.3 billion figure represented the largest hack by dollar value, the comparison becomes significantly different when measured against bitcoin's total supply at the time of the incident.
Zhao referenced the 2011 collapse of Mt. Gox, which involved approximately 650,000 BTC—representing more than 5% of bitcoin's total supply at that time. He suggested that investors should evaluate security incidents beyond their dollar value, considering instead the percentage of crypto supply involved, the number of users affected, the proportion of user assets lost, and which party absorbs the losses.
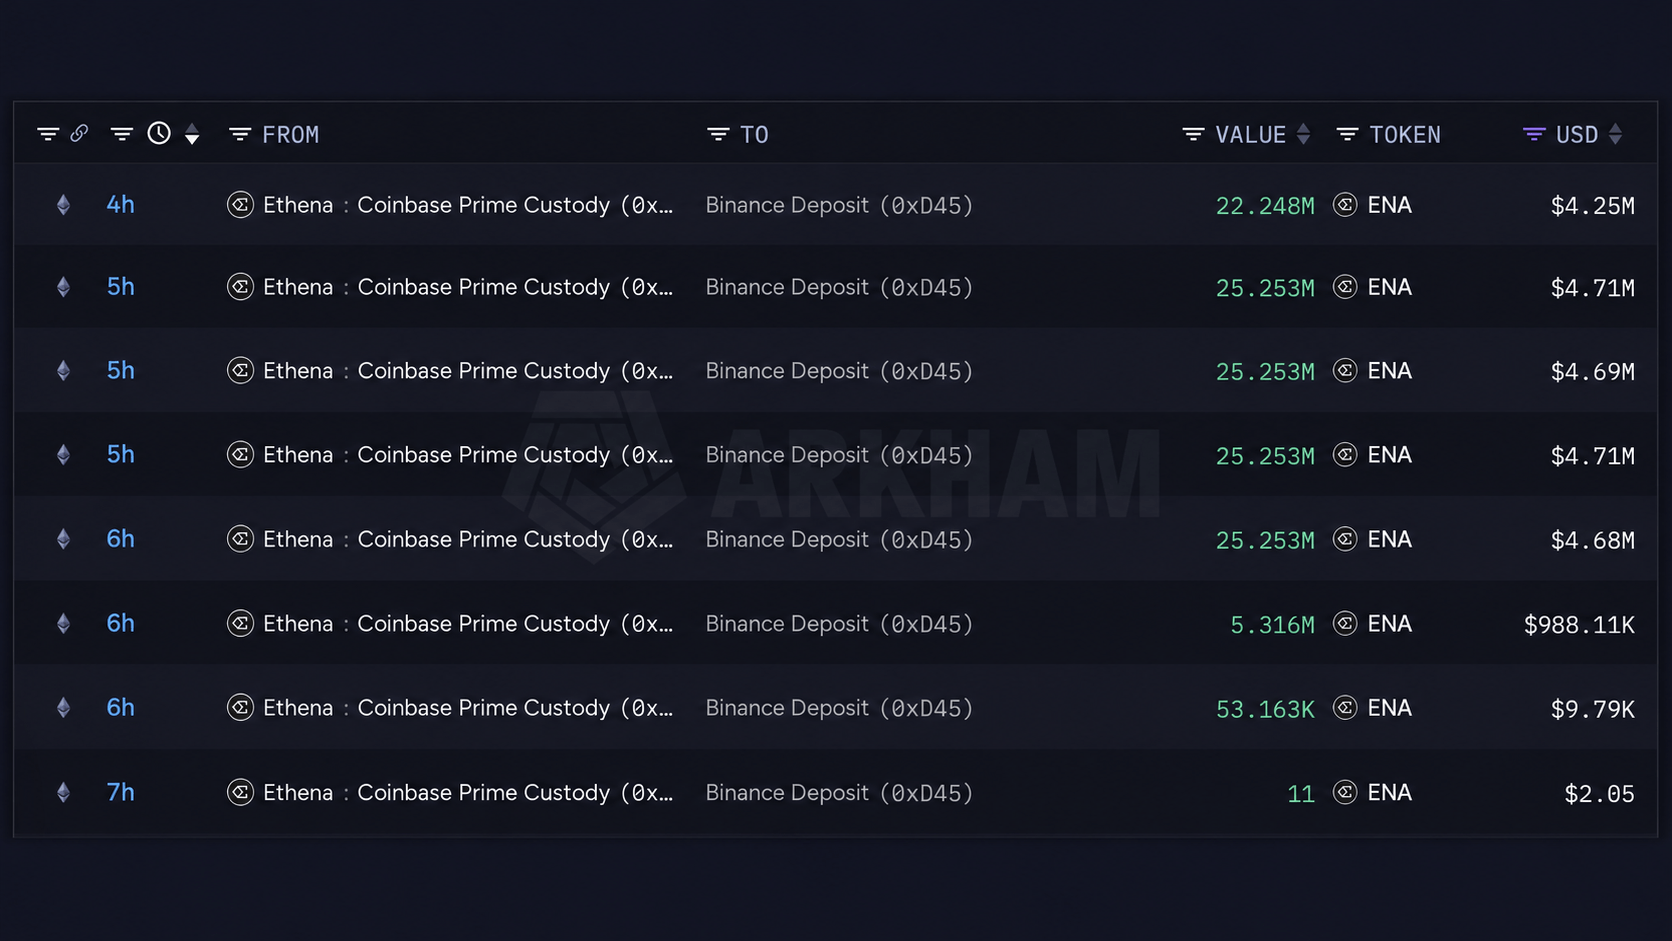
Unlike the Mt. Gox failure and the 2022 FTX collapse, where a significant proportion of customers and their assets were caught up in the collapses, Binance committed to absorbing the full $6.3 billion loss rather than distributing it to its user base. The exchange stated it had already set aside more than $6.3 billion in company funds, including $5 billion in assets matching those affected by the breach, covering approximately 80% of the losses. The remaining amount would be purchased through market and over-the-counter channels, which on-chain data subsequently confirmed.