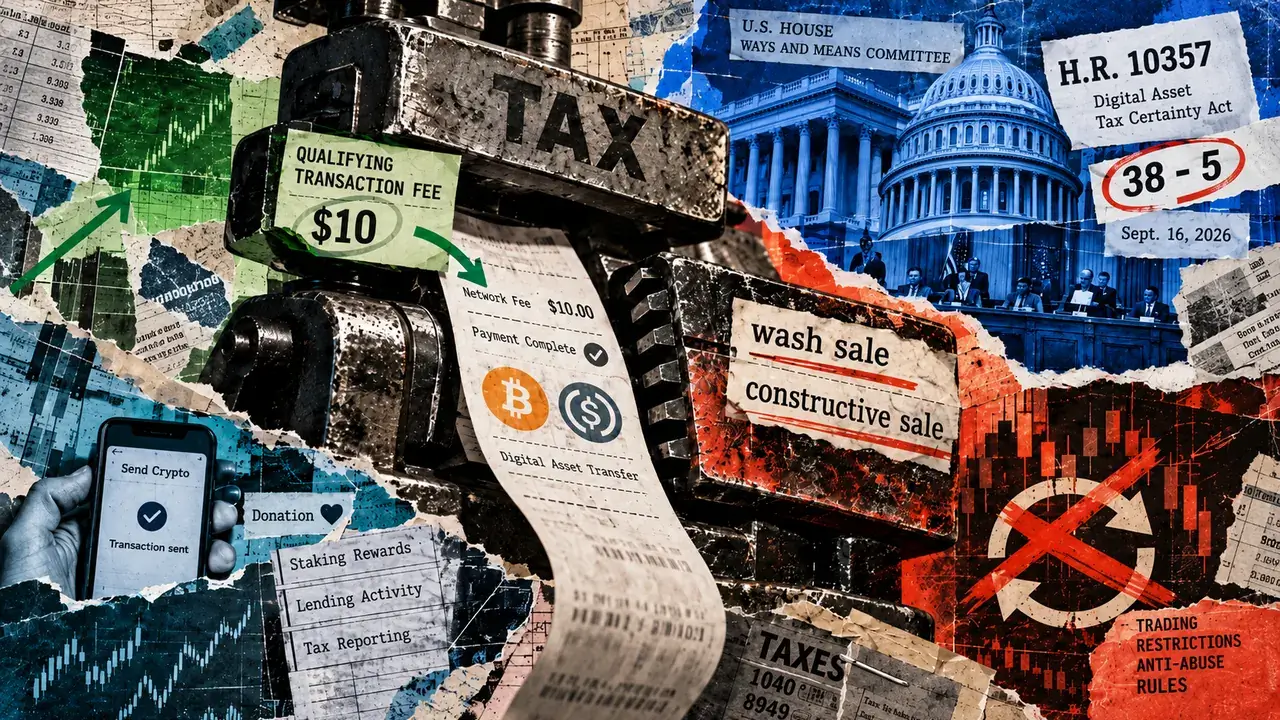
The House Ways and Means Committee approved H.R. 10357, the Digital Asset Tax Certainty Act, on September 16 by a vote of 38-5, advancing the first comprehensive digital-asset tax framework toward the full House.
The legislation addresses taxation of crypto payments, stablecoins, trading, lending, staking, and mining. However, industry groups have signaled that several priorities remain unresolved as the bill moves forward.
Payment Relief Remains Limited
The bill would eliminate gain-or-loss recognition when digital assets are used to pay qualifying network and transaction fees of no more than $10, effective for dispositions after December 31, 2027. Currently, the Internal Revenue Service treats digital assets as property, meaning using crypto to pay blockchain fees can create a taxable event.
The Crypto Council for Innovation called this progress but urged Congress to expand de minimis relief for everyday digital-asset transactions beyond the narrow $10 fee provision.
Staking Income Timing Unresolved
The legislation establishes that income from digital-asset validation activities—staking and mining—constitutes ordinary income and creates sourcing rules based on taxpayer location. However, the bill does not include optional deferral provisions that would allow miners and stakers to delay recognizing newly created tokens as income until sale.
Industry advocates sought this deferral to address cases where validators receive token rewards without cash, creating immediate tax liability before tokens are liquidated. Price movements between receipt and sale can leave miners and stakers exposed to significant tax obligations.
Additional Provisions and Trade-Offs
The package provides special treatment for qualifying US dollar stablecoins, simplified accounting elections for widely traded digital assets, and extends financial-market treatment to lending, mark-to-market accounting for eligible dealers and traders, and charitable donation rules.
The legislation also tightens rules on investors by extending wash-sale and constructive-sale provisions to digital assets, closing tax strategies previously available because cryptocurrencies fell outside existing securities regulations.
The bill includes provisions addressing foreign entities associated with decentralized autonomous organizations, directing Treasury to issue guidance within 12 months on their tax treatment and allowing qualifying foundations to reorganize as domestic corporations.