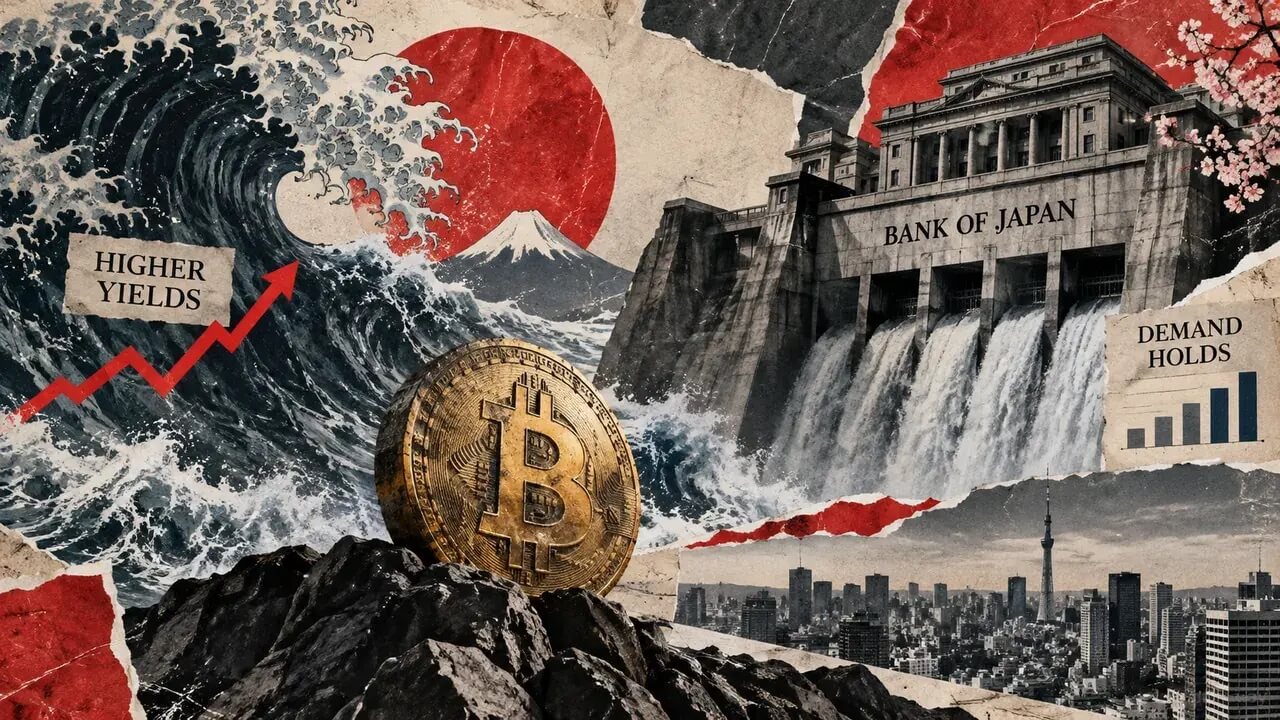
Japan's 20-year government bond auction on Tuesday cleared at an average yield of 3.856%, up 15.8 basis points from the previous month's 3.698%. The sale showed slightly improved bid coverage at 4.01 times, compared to 3.98 times in August, with a narrower yield tail of 1.3 basis points versus 1.5 basis points previously.
The auction results reflect orderly absorption at higher yields rather than demand collapse. However, the repricing signals a notable shift in long-term borrowing costs that extends beyond the immediate transaction.
Carry Trade Implications
The higher yield environment presents a potential risk to leveraged Bitcoin positions. Investors who borrow yen at relatively low short-term rates to finance positions in higher-returning assets face pressure if borrowing costs rise or the yen strengthens, making loans more expensive to repay.
Tuesday's bond yield, however, reflects long-term pricing rather than the short-term funding rates that directly drive carry trades. Cross-market signals immediately following the auction—including the yen trading weaker against the dollar, equities modestly higher, and Bitcoin near $77,700—showed no synchronized deleveraging pattern.
Market Context and Next Trigger
The Bank of Japan's August survey had forecast a median 20-year yield of 3.70% by end-September, with an upper quartile of 3.75%. The auction's 3.856% result significantly exceeds that range, indicating substantial repricing in the long end of Japan's bond market.
The BOJ's April Financial System Report noted Japan's financial system as stable overall, though it highlighted rising bond valuation losses and relatively large securities losses at shinkin banks. The higher yield environment intensifies these pressures without confirming financial disorder.
The Bank of Japan's scheduled meeting on September 17–18 represents the next potential catalyst. For Bitcoin and leveraged positions, the critical signal will be whether BOJ policy decisions and currency movements convert Japan's gradual repricing into a coordinated cross-asset adjustment.