Professional automated market makers, or propAMMs, deliver significantly better execution prices on Solana trades compared to public pools, according to a September preprint study covering the period from September 1, 2025, through August 31, 2026.
For quiet-market SOL/USDC transactions, propAMMs showed execution costs of 0.26 basis points against 2.59 basis points for public automated market makers, measured by reference-relative proxy. The research, authored by scientists affiliated with ETH Zurich and Category Labs, weighted fills by notional value against Bybit's size-weighted top-of-book USDT microprice.
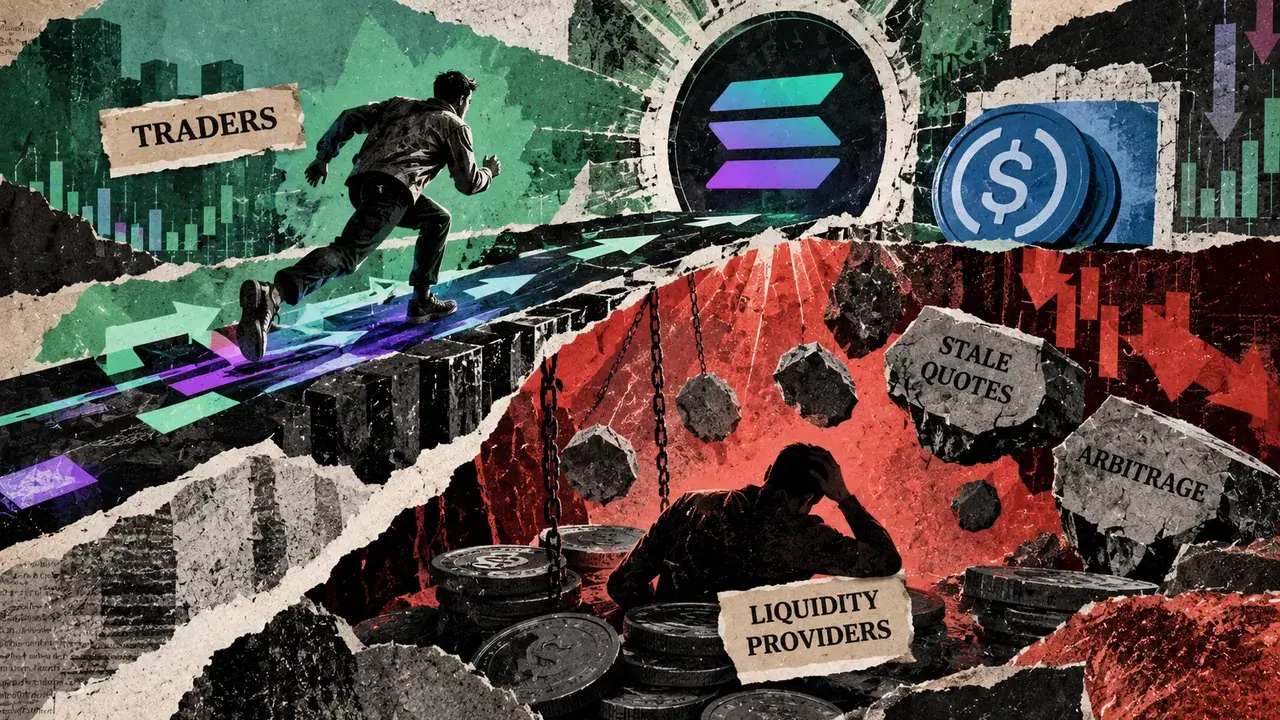
The efficiency gap reflects different economic incentives for traders and liquidity depositors. Traders benefit from tighter pricing, but passive pool depositors face exposure to arbitrage losses when market prices move faster than pools can update their quotes.
Maker Returns Tell a Different Story
While swappers enjoy cost advantages, the data on pool profitability reveals tension. Across the Solana sample, propAMMs recorded two-second gross maker markouts of positive 0.37 basis points, meaning trades favored the pool operator. Public AMMs recorded negative 0.22 basis points, indicating losses to passive liquidity providers.
Lower swap costs do not automatically translate to positive returns for liquidity providers. When outside market prices move first, pools offering stale quotes can be forced to trade at disadvantageous prices. Arbitrageurs profit from correcting these mismatches, but the cost falls on existing liquidity.
The Broader Return Picture
A complete assessment of liquidity provider economics requires accounting for multiple factors beyond execution spreads: asset exposure, trading fees, inventory changes, hedging costs, and transaction expenses. The study's short time horizon leaves this broader accounting unresolved, and aggregate venue data cannot definitively establish that professional pools caused passive-LP losses.
Professional operators can adjust pricing and available liquidity based on inventory levels, quote freshness, and flow quality. Tighter quotes under lower-risk conditions create an economic case for professional operation, though implementations vary by operator.
Quote Reliability Questions Emerge
On the Base blockchain, execution on Tessera averaged 1.08 basis points worse by individual trade and 0.56 basis points worse by volume when compared to reconstructed previous-block-end quotes. Researchers noted a block-timed fee pattern they described as a concern for quote reliability, though the data provides no direct evidence of intentional manipulation.
The gap between advertised quotes and delivered execution creates routing challenges. Routers comparing executable prices at transaction time rather than earlier quotes can improve outcomes, but effectiveness depends on whether all venues are consistently reconsidered within a single transaction and whether comparisons account for all applicable fees and caller-specific terms.
What Comes Next
Meaningful assessment of swap routing requires comparing quoted and delivered output on matched transactions, explaining which costs are included, and demonstrating how routing engines treat persistently underperforming sources. For passive liquidity providers, separate position-level return analysis is needed to determine whether improved routing benefits extend beyond traders to pool depositors.