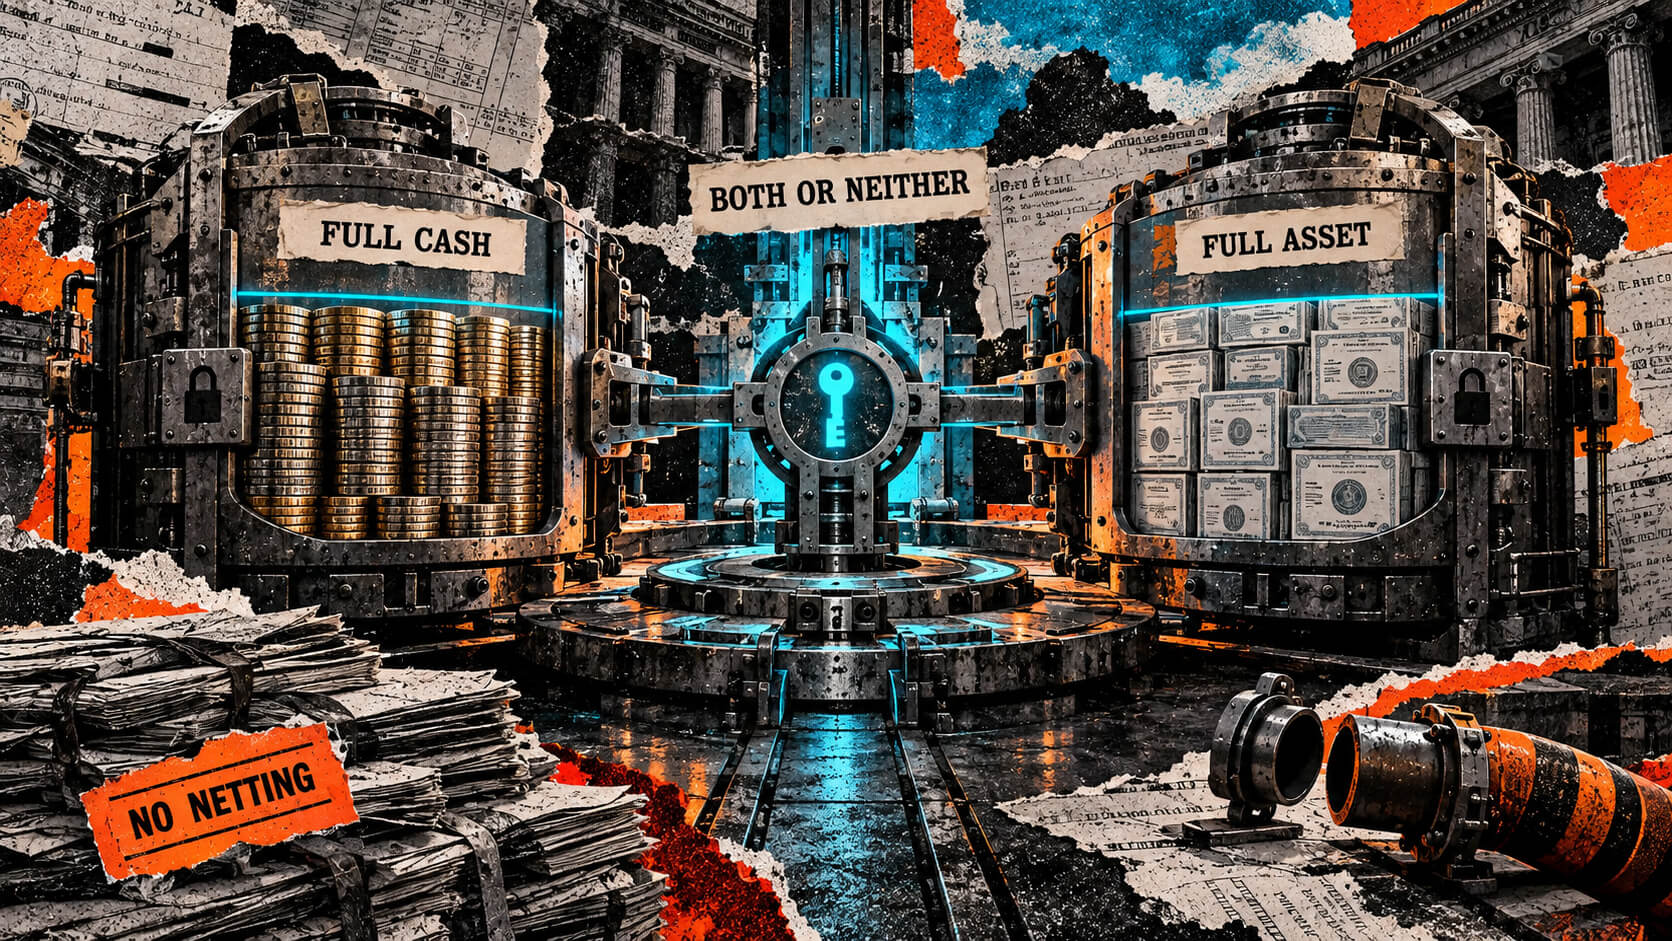
The Solana Foundation announced Solana DvP on October 6 as an open-source standard for delivery-versus-payment settlement. The program's published design requires the full cash and asset legs of a trade to be available before execution, preventing a buyer from paying without receiving the asset through an atomic transaction.
Under the program, each side's tokens are placed into separate escrows, then both agreed amounts move together. The design explicitly excludes netting, the process of offsetting obligations before paying the remaining balance.
Funding Requirements
One trade record covers one exchange between two parties, with both legs required to be token accounts on Solana. Partial fills are not allowed, and the settlement code checks that each escrow balance meets the agreed amount before transferring either leg.
If either side is underfunded, settlement fails and excess tokens are returned to the named party. Participants must arrange their own cash tokens, asset tokens, and any necessary financing through separate arrangements outside the DvP program.
A custody or treasury system can supply tokens through ordinary checked token transfers. Both balances must meet agreed amounts at settlement, and a settlement authority must sign to execute the exchange.
Speed Versus Capital Requirements
Institutions may benefit from faster access to proceeds, potentially reducing how long they need external financing or how much liquidity they hold against a sequence of obligations. However, the program does not perform calculations to offset obligations across trades.
The Bank for International Settlements and the Committee on Payments and Market Infrastructures noted in their October 2024 tokenization report that immediate gross settlement can require more liquidity than netting arrangements, though quicker access to money and assets can reduce the opportunity cost of liquidity tied up during settlement.
The resulting total cost for institutions depends on the funding arrangement and timing of usable proceeds. The Foundation's announcement provides no measured capital-saving result or total-cost comparison.
Protection and Risks
The atomic exchange protects against principal delivery risk within the token exchange: neither side transfers its agreed leg without the other leg also moving. However, the broader financial relationship depends on the instruments being exchanged.
A cash token carries its issuer's credit and redemption risks, and regulated asset tokens can retain controls affecting transfers. Freeze, pause, and permanent-delegate powers remain relevant while tokens sit in escrow. A fully funded trade can still fail to complete if an issuer freezes an escrow or blocks transfers.
Current Status
The Foundation's documentation lists an upgradeable program on mainnet-beta and devnet with observations dated October 2. Security reviewer Cantina conducted an audit from May 21-28 covering an earlier repository version, with four medium findings marked fixed and nine lower-risk findings acknowledged.
The Foundation says the program is ready for real funds while inviting design partners and early participants ahead of production release. JPMorgan supplied securities-settlement-practice input but expressly disclaimed any role in the program's design, development, operation, approval, endorsement, or guarantee.