Understanding the Strategy Pricing Dashboard
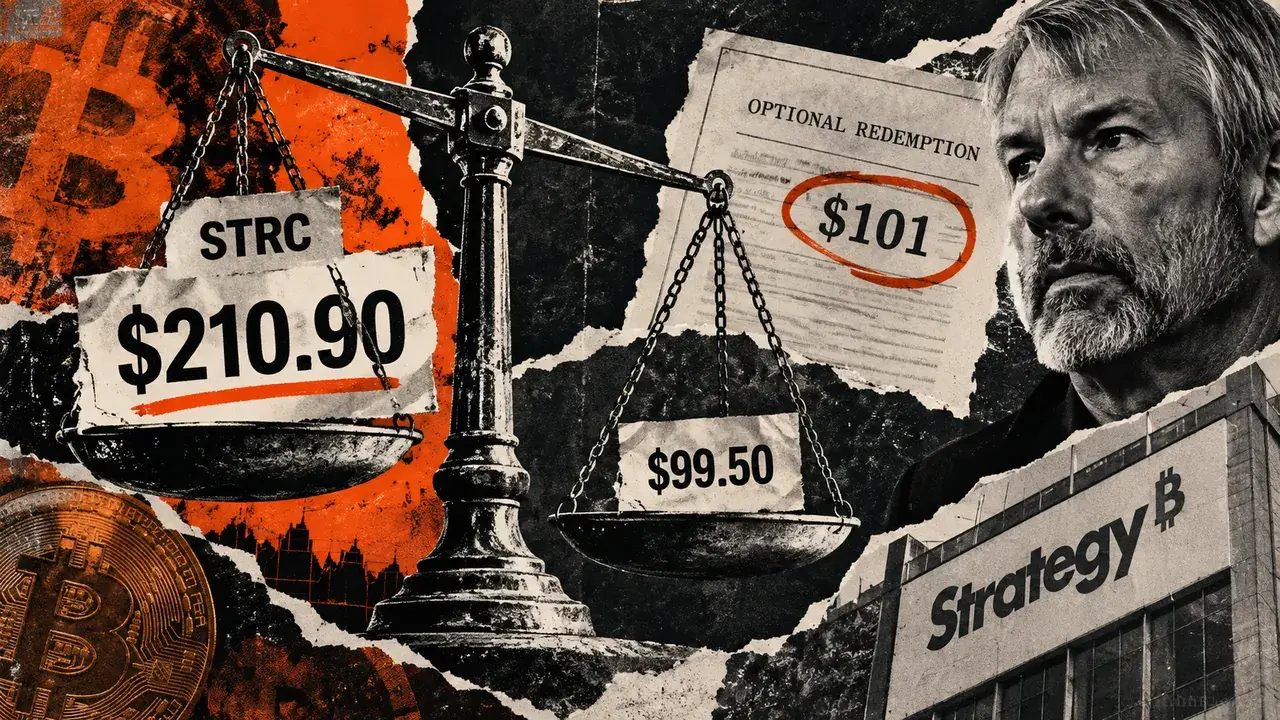
Strategy’s Bitcoin credit calculator produced an illustrative STRC price of $210.90 on Oct. 2, while displaying a market-price input of $99.50 for the perpetual preferred stock. The issuer also retains the option to redeem shares at $101, or a higher amount it chooses, plus applicable unpaid dividends.
That gap exposes the limits of the calculation. The published formula holds the current dividend constant and replaces the market’s credit spread with a modeled Bitcoin spread. It contains no explicit valuation of the issuer’s call option or a path for future dividend resets. Strategy’s pricing dashboard separately discloses those features and warns that the call can make the derived price diverge substantially from realizable market prices.
For buyers, the calculation is a view of the security under selected assumptions. It does not establish that STRC is worth more than twice its displayed market price, or that a holder can collect either the model output or the redemption amount on demand.
How the Calculator Reaches the Model Output
At approximately 08:18 UTC on Oct. 2, the dashboard used a Bitcoin price input of $86,593, an assumed annual return of 10%, and volatility of 40%. Its STRC row showed a 12.06% effective yield, a 5.23% risk-free yield, and 46 basis points of BTC Credit, which represents Strategy’s modeled credit spread.
The published pricing formula divides the annual dividend by the sum of the risk-free yield and BTC Credit. Using a $12 annual dividend and the displayed inputs yields approximately $210.90.
Strategy expressly states that the output is neither a fair-value determination nor a price target. Its assumptions include full scheduled payments and a simplified treatment of Bitcoin coverage and claims. The dashboard also warns that displayed market prices can be stale and are not executable quotes.
Redemption Terms and Issuer Options
Under STRC’s amended certificate of designations, Strategy can elect optional redemption at $101 per share or a higher amount it announces, alongside applicable accumulated unpaid dividends and compounding. A partial optional redemption must leave at least $250 million of stated amount outstanding and uncalled when notice is provided.
These terms govern an issuer action rather than an ordinary holder right to cash out. If Strategy exercises the option, the holder receives the contractual redemption payment instead of continuing to own the dividend-paying share. However, the $101 figure neither promises a redemption nor imposes an absolute secondary-market price ceiling, and buyers cannot assume the company will redeem merely because STRC trades below that level.
Dividend Mechanics and Payment Schedules
The numerator in the pricing formula is also adjustable, as STRC’s current rate does not promise the same cash income indefinitely. STRC dividends accumulate cumulatively, though cash payment requires board declaration and legally available funds.
The payment calendar has shifted from a monthly schedule to twice-monthly payments, with a daily-dividend proposal awaiting an Oct. 28 shareholder vote. Strategy’s Oct. 1 filing reported that its Sept. 30 action maintained the 12% annual rate for periods beginning Oct. 16 and declared a $0.50 payment for the semi-monthly period ending Oct. 31. More frequent payments change when income arrives, but do not create a daily redemption right, lock in the dividend rate, or guarantee principal stability.
Bitcoin Coverage Versus Dollar Capacity
Strategy’s Bitcoin holdings and its cash-payment resources answer separate questions. Bitcoin coverage concerns assets relative to claims under model assumptions, whereas dividends payable in dollars require actual dollar capacity when payment comes due.
In its Sept. 28 reserve update, Strategy reported a $5.02 billion USD Reserve and a separate $1.00 billion USD Cash balance as of Sept. 27. Claim priority also matters, as debt and STRF sit above STRC, while Bitcoin is not pledged directly to STRC holders. Ultimately, at the Oct. 2 snapshot, the calculator’s large gap to the displayed market price resolved none of the underlying contractual and payment questions.