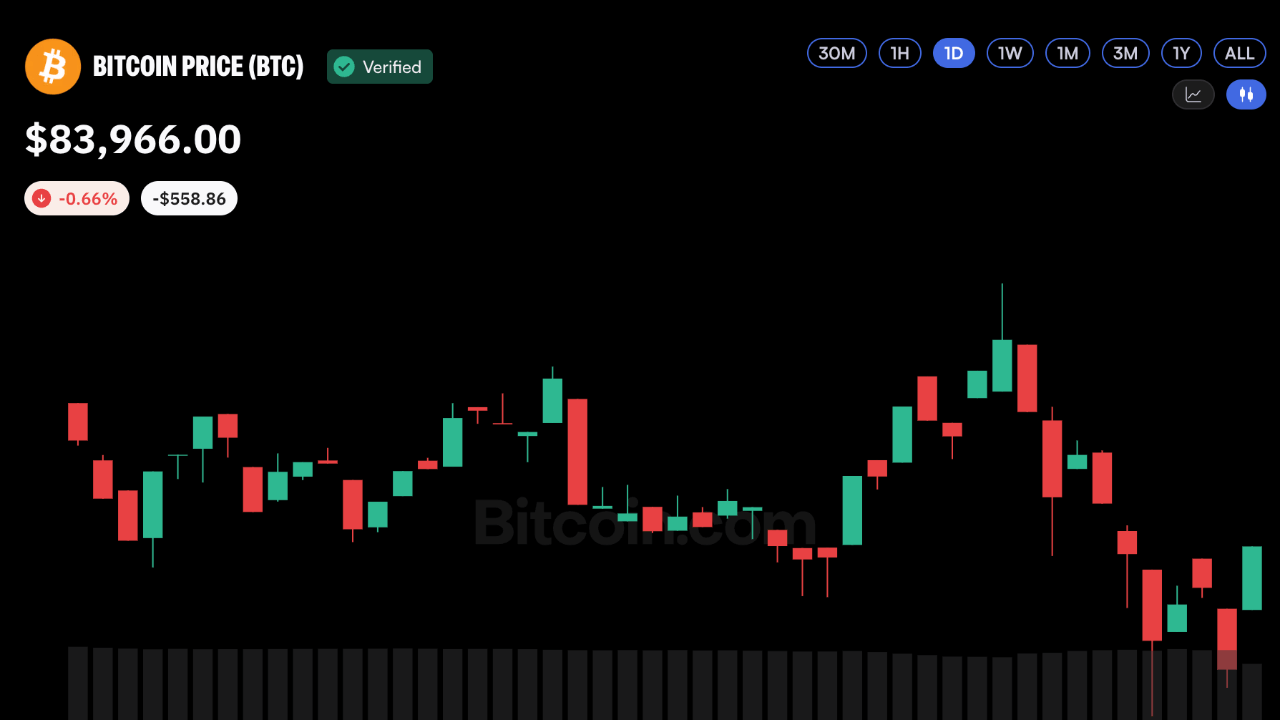
Bitcoin has advanced above several important investor cost bases following a roughly $10,000 gain over ten days, with onchain data suggesting the market experienced stress without reaching previous capitulation conditions. The largest cryptocurrency by market cap has not closed below its Realized Price during recent downturns, and the percentage of supply held in profit remains comparable to 2022 levels despite broader market pressure.
A significant concentration of long-term-holder coins sits around $84,000 to $85,000, creating a natural level where investors may consider taking profits. Beyond that zone, the mean MVRV price near $96,700 represents the next major onchain resistance level. Profit-taking remains subdued even as short-term holders return to profit, with selling occurring at only a fraction of levels recorded during 2024 and 2025 market peaks.
Spot market demand is improving alongside ETF buying activity. Trading volume has more than doubled from its August low, with strengthening institutional participation across multiple exchanges. Rallies backed by spot buying carry a different risk profile than moves dominated by derivatives leverage.
Around 167,000 Bitcoin options contracts carrying roughly $14.04 billion in notional value expire on September 25, representing approximately 32 percent of total bitcoin options open interest. The contracts carry a put-call ratio of 0.87 and a maximum-pain level of $79,000. Dealer positioning has concentrated heavily around $84,000 ahead of settlement, with gamma exposure expected to shift higher above $90,000 after expiry.
The broader cryptocurrency market has participated in the recovery, with altcoins rising across the board. Traders have added relatively little leverage compared with the scale of the move, while implied volatility remains relatively contained. Much of the activity around expiry has involved traders rolling positions rather than making aggressive directional bets.
Bitcoin's price stands at a transition point with the $84,000-$85,000 supply zone under pressure and institutional demand improving. If spot and ETF buying continue absorbing supply, market attention could shift toward $90,000, $95,000, and ultimately the $96,700 MVRV level after the options expiry clears.