The Securities and Exchange Commission's Division of Corporation Finance released guidance distinguishing between staking receipts and protocol-issued tokens, clarifying that a token's label does not determine its regulatory status or guarantee immediate conversion to unstaked ethereum.
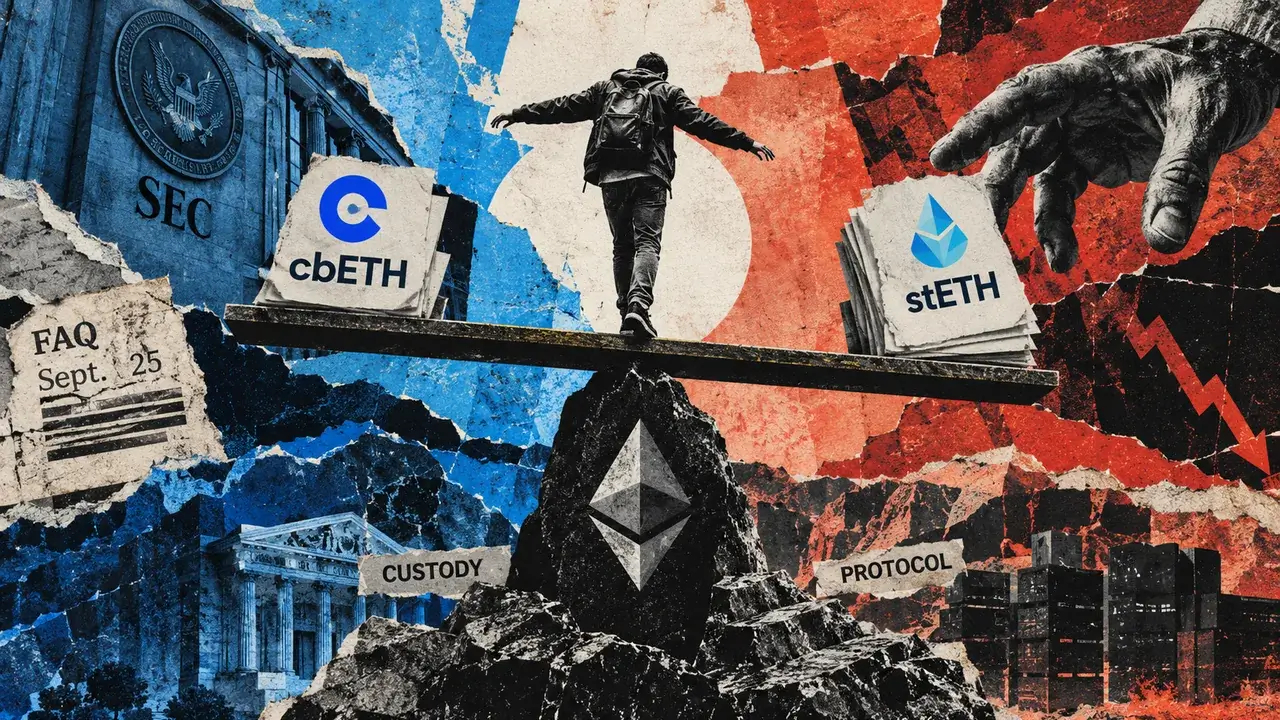
In a September 25 staff FAQ, the SEC defined a qualifying staking receipt for a digital commodity as a "digital tool" that evidences ownership of deposited assets while the receipt issuer retains no control or claim on those assets. A token issued by a protocol-based liquid-staking provider may instead be classified as a "digital commodity" when its value is linked to a functioning crypto system and market supply and demand. The guidance does not name specific products such as Coinbase's cbETH or Lido's stETH.
Two Different Redemption Routes
Coinbase's custodial model holds staked ETH on behalf of token holders, with ownership remaining with the depositor. A cbETH holder can sell the token on secondary markets or redeem it contractually through Coinbase, provided they maintain an eligible account and meet staking requirements. However, selling cbETH in the market does not guarantee a buyer at any particular price, and Coinbase warns that the token's price can diverge from ETH or staked ETH. Redemption through unwrapping returns staked ETH but requires an additional unstaking request to obtain spendable ETH, a process that involves further delays.
Lido's protocol model operates differently. Token holders deposit ETH into the smart contract and receive stETH. To reclaim ETH through the protocol, holders submit a withdrawal request that enters a queue. The token can alternatively be sold to another trader. According to Lido's risk disclosure, protocol withdrawals can be slowed by queue capacity and Ethereum validator exits. Secondary-market sales offer faster liquidity only if traders are available at acceptable prices; spreads and slippage can widen when liquidity is constrained.
The Limits of "Liquid"
The term "liquid" describes a token's ability to be transferred, not a guaranteed conversion to unstaked ETH at a fixed value. With both cbETH and stETH, holders face secondary-market price divergence from the underlying staked position's value, as well as product-specific constraints on redemption timing and eligibility.
The SEC guidance does not classify either token by name, and the staff FAQ creates no new obligations. The guidance emphasizes that before treating a liquid-staking token as interchangeable with ETH, an investor should understand who retains ownership of the deposit, who operates the redemption path, what asset is returned first, and which delays or losses can occur during the process.